Stablecoins vs. Banks: A New Financial Frontier or a False Dawn?
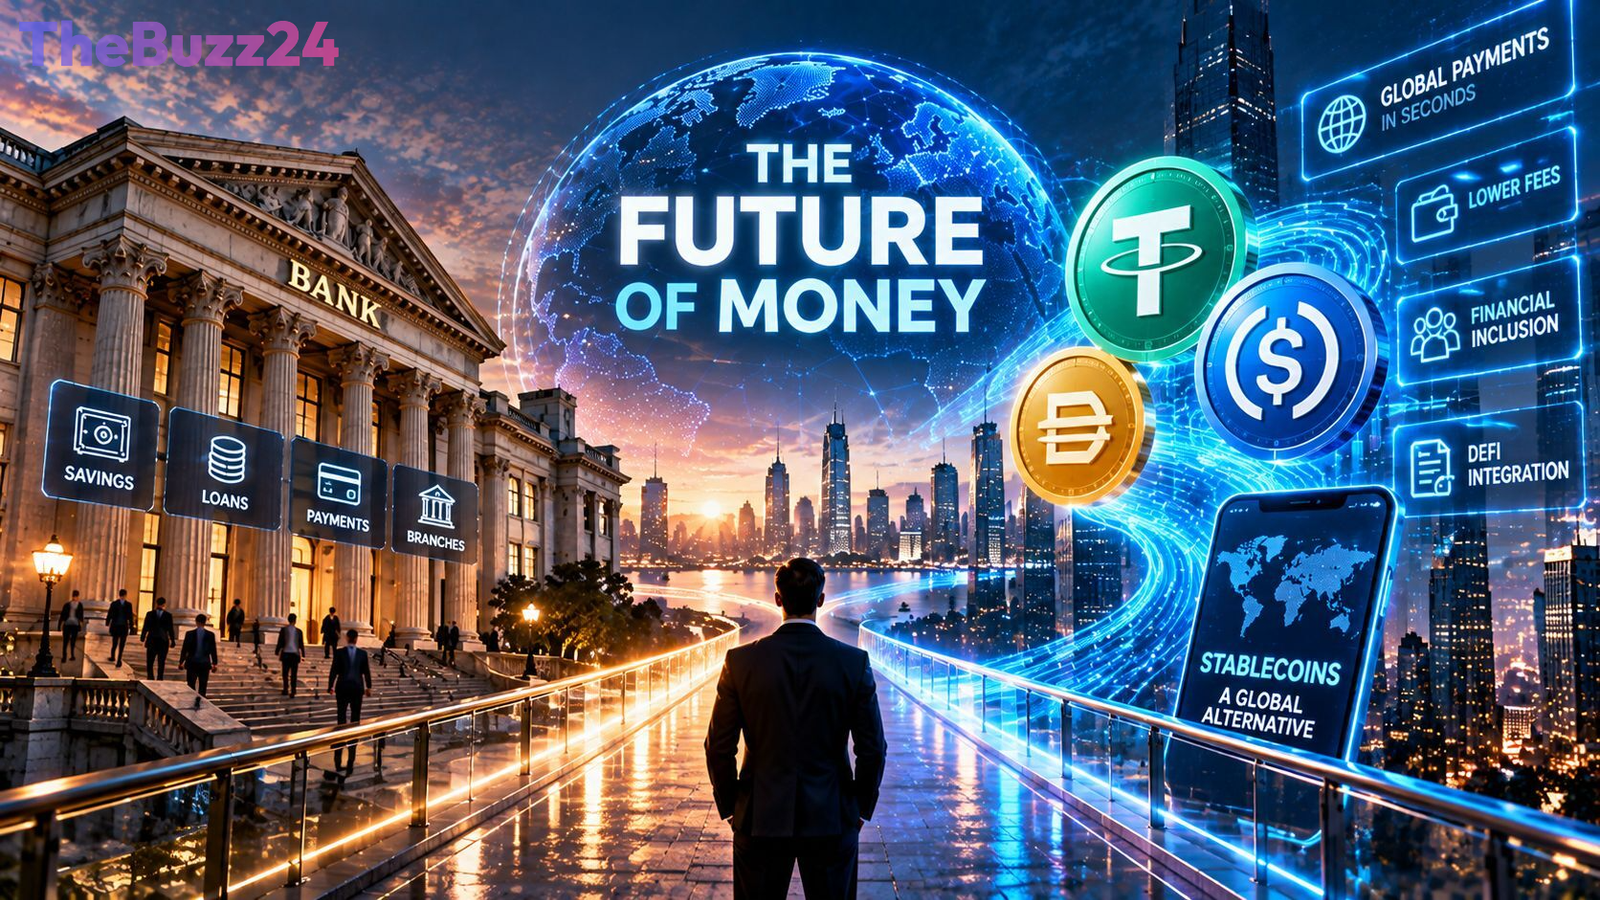
The global financial landscape is on the cusp of a significant transformation, with stablecoins emerging as a potent challenger to traditional banking models. These digital assets, designed to maintain a stable value against fiat currencies, offer a new paradigm for money transfer and storage, raising critical questions about the future role of established financial institutions. While stablecoins excel at facilitating rapid blockchain-based transactions, their ability to fully replace the comprehensive services offered by banks, such as lending, credit underwriting, and regulatory oversight, remains a subject of intense debate and ongoing research.
The core of the competition lies in the distinct functions of banking and stablecoin issuance. Banks provide a suite of services including deposit-taking, payment processing, and crucially, credit creation. Stablecoins, on the other hand, primarily offer an alternative to traditional payment rails and a means of holding value digitally. Although some stablecoins are backed by reserves held in traditional assets like U.S. Treasury securities, they do not inherently offer the same level of consumer protection, such as deposit insurance, nor do they automatically replicate the complex risk assessment and lending functions that underpin bank operations. This fundamental difference suggests that while stablecoins may disrupt specific banking services, particularly payments, they are unlikely to supplant the entirety of the banking system in the near future.
Research indicates that the growing adoption of stablecoins could have tangible effects on the banking sector. Potential impacts include shifts in bank deposit funding, altered lending capacities, and changes in the demand for government securities used as reserves. As stablecoin issuers increasingly integrate with traditional financial infrastructure, banks may face new liquidity demands and potentially adjust their lending portfolios. Furthermore, the growth of dollar-denominated stablecoins could have broader implications for global monetary policy and the international role of currencies, particularly in emerging economies. The future may thus see a hybrid financial system where traditional banking and digital assets coexist, driven by innovation, regulatory frameworks, and evolving consumer and business needs.
The trajectory of stablecoins and their impact on banking will be heavily influenced by regulatory developments and the ability of these digital assets to build and maintain user trust. While the technology offers efficiency gains, the absence of established consumer protections and the inherent risks associated with reserve management and redemption processes present significant hurdles. Ultimately, the competition may not be about replacing banks entirely, but rather about forcing the entire financial ecosystem to innovate, potentially leading to more integrated and efficient financial services for consumers and businesses alike.
Key Takeaways
- Stablecoins offer faster, blockchain-based money transfers but do not replicate the full range of banking services like lending and credit underwriting.
- The growth of stablecoins could impact bank funding, liquidity, and lending, potentially leading to a more integrated financial system rather than a complete replacement of banks.
- Regulatory clarity and consumer trust are crucial factors that will shape the adoption of stablecoins and their long-term influence on the financial industry.
Editor’s Analysis & Impact
The rise of stablecoins presents a compelling case study in financial innovation, challenging the long-standing dominance of traditional banks in payment systems. While the technology promises efficiency and accessibility, its true impact hinges on its ability to navigate complex regulatory landscapes and build robust consumer trust. The potential for stablecoins to disrupt bank funding models and influence credit markets is significant, suggesting a future where hybrid financial systems, integrating both traditional and digital assets, become the norm. This evolution could spur competition, leading to improved financial services, but also necessitates careful oversight to maintain financial stability and protect consumers. The interplay between innovation, regulation, and market adoption will ultimately define the new frontier of digital finance.
Frequently Asked Questions
Q: Can stablecoins completely replace traditional banks?
A: It is unlikely that stablecoins will completely replace traditional banks. While they can challenge and potentially disrupt specific banking functions like payments and money holding, they do not inherently offer the comprehensive services such as credit underwriting, lending, and regulatory compliance that banks provide.
Q: What are the main risks associated with stablecoins compared to bank deposits?
A: Stablecoins carry risks such as reserve volatility, issuer insolvency, redemption difficulties, and operational failures, which are not typically present in insured bank deposits. Bank deposits often benefit from government insurance and are backed by regulated financial institutions, offering greater security.
Q: How might stablecoins affect the cost of international remittances?
A: Stablecoins have the potential to reduce the cost and increase the speed of international remittances by bypassing some traditional intermediaries. However, the overall cost depends on various factors including currency conversion fees, blockchain transaction fees, and local withdrawal charges, meaning they are not universally cheaper than existing methods.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category