The Elusive ‘Good Debt’: Experts Unpack Historical Inequality and Modern Anxiety
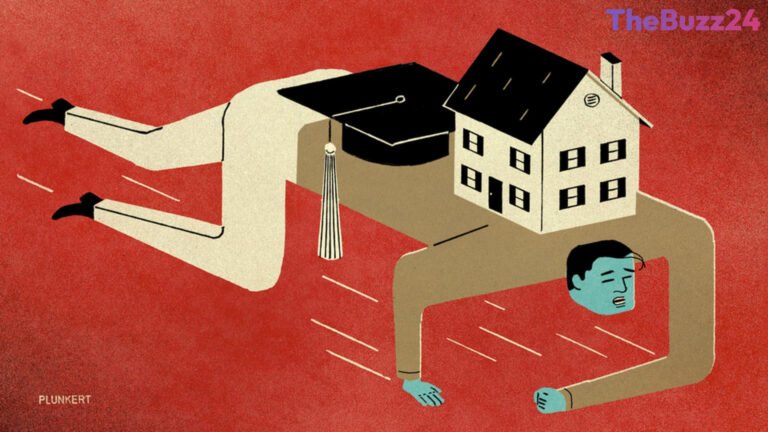
The concept of ‘good debt’—borrowing that can lead to wealth accumulation—has been a subject of debate and societal stratification for centuries. Experts from diverse fields, including sociology, philosophy, history, and theology, suggest that access to beneficial debt has never been equitable, with historical and systemic factors creating a persistent two-tiered system.
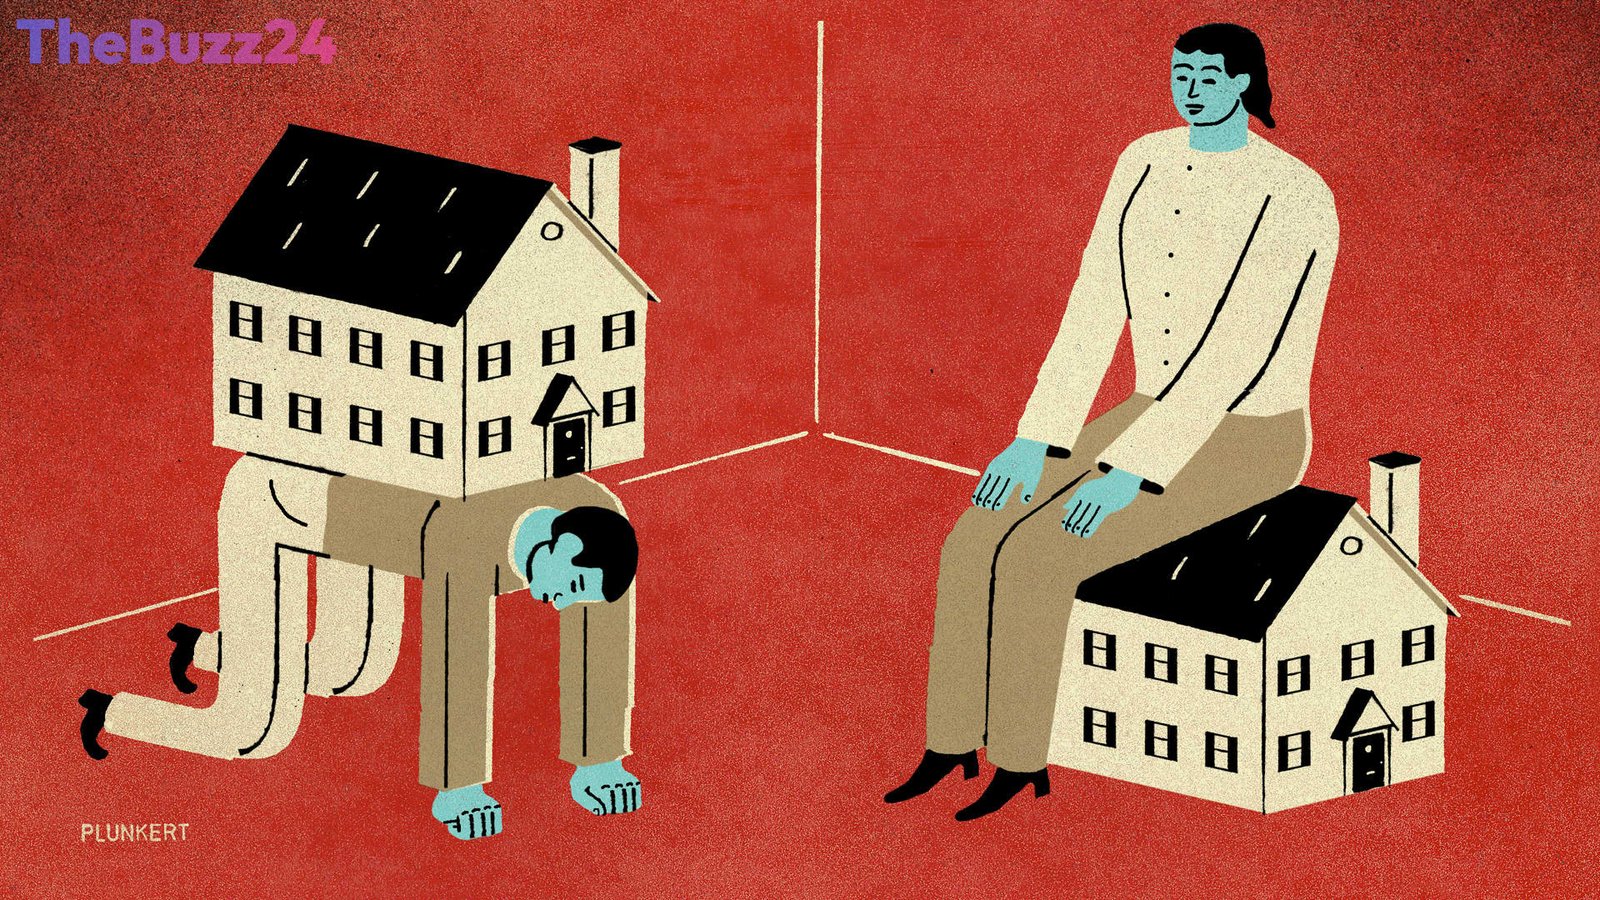
Sociologist Frederick Wherry of Princeton University points to the ‘Matthew effect,’ where those who already possess resources are more likely to receive further advantages, including access to favorable credit. Conversely, individuals in financial distress often face higher interest rates and less favorable terms, perpetuating a cycle of disadvantage. Wherry highlights that while low-income individuals may have access to financial aid and some protections, the middle class often finds itself navigating a more precarious debt landscape, bearing a significant burden.
Historically, attitudes towards debt have evolved dramatically. In ancient Rome, debt was often viewed with severe negativity, with debtors facing harsh penalties. By the 1920s in America, however, debt began to be embraced as a tool for acquiring new technologies like automobiles. Historian Louis Hyman notes that the New Deal era in the 1930s established a credit system largely designed to benefit white, middle-class, married men, leaving marginalized groups, such as Black Americans and single women, with limited or no access to the expanding credit opportunities, particularly in housing.
Philosophical perspectives, dating back to Plato, link the ability to manage and prevent debt with a form of justice and happiness. However, philosopher Graham Hubbs observes that as the costs of essential items like homes and education outpace income growth, the prospect of assuming ‘good debt’ becomes increasingly unattainable for many, leading to stress and anxiety. Financial therapist Sonya Lutter adds that current economic uncertainty exacerbates this anxiety, making individuals perceive ‘good debt’ as an option only for the wealthy, even if their own financial situations might allow for it.
Key Takeaways
- Access to 'good debt' has historically been unequal, favoring certain demographic groups over others.
- Societal and economic structures, including historical policies and the 'Matthew effect,' contribute to persistent disparities in credit access.
- Modern economic conditions and psychological perceptions of debt create anxiety, making 'good debt' seem unattainable for many.
Editor’s Analysis & Impact
This exploration into the nature of ‘good debt’ reveals a deeply ingrained societal issue rooted in historical inequities and perpetuated by current economic pressures. The insights from sociology, history, and philosophy underscore that favorable credit is not merely a financial product but a reflection of power structures and social stratification. As the cost of living and education continues to rise, the gap between those who can leverage debt for wealth creation and those who are burdened by it is likely to widen. This trend has significant implications for social mobility and economic stability, potentially leading to increased financial anxiety and social unrest if not addressed through more inclusive financial policies and accessible credit frameworks.
Frequently Asked Questions
Q: What is considered 'good debt'?
A: 'Good debt' is typically defined as borrowing that is used to acquire assets that are expected to increase in value or generate income, such as a mortgage on a home or student loans for education that leads to a higher-paying career. It's debt that, if managed responsibly, can improve one's financial standing.
Q: Why is access to 'good debt' unequal?
A: Access is unequal due to a combination of historical factors, systemic biases, and current economic conditions. Historically, credit systems were often designed to favor certain groups. Today, factors like income level, credit history, and even perceived creditworthiness, influenced by societal biases, can limit access to favorable loan terms for many individuals.
Q: How does the 'Matthew effect' relate to debt?
A: The 'Matthew effect' suggests that those who have more tend to receive more, while those who have less tend to lose what little they have. In the context of debt, it means that individuals who are already financially stable and don't necessarily need debt are more likely to qualify for and receive 'good debt' with favorable terms, further enhancing their financial position. Conversely, those in financial distress often face more restrictive and costly debt options.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category