General Motors Outpaces Q3 Estimates, Ups Cash Flow Target, and Unveils $20B Buyback
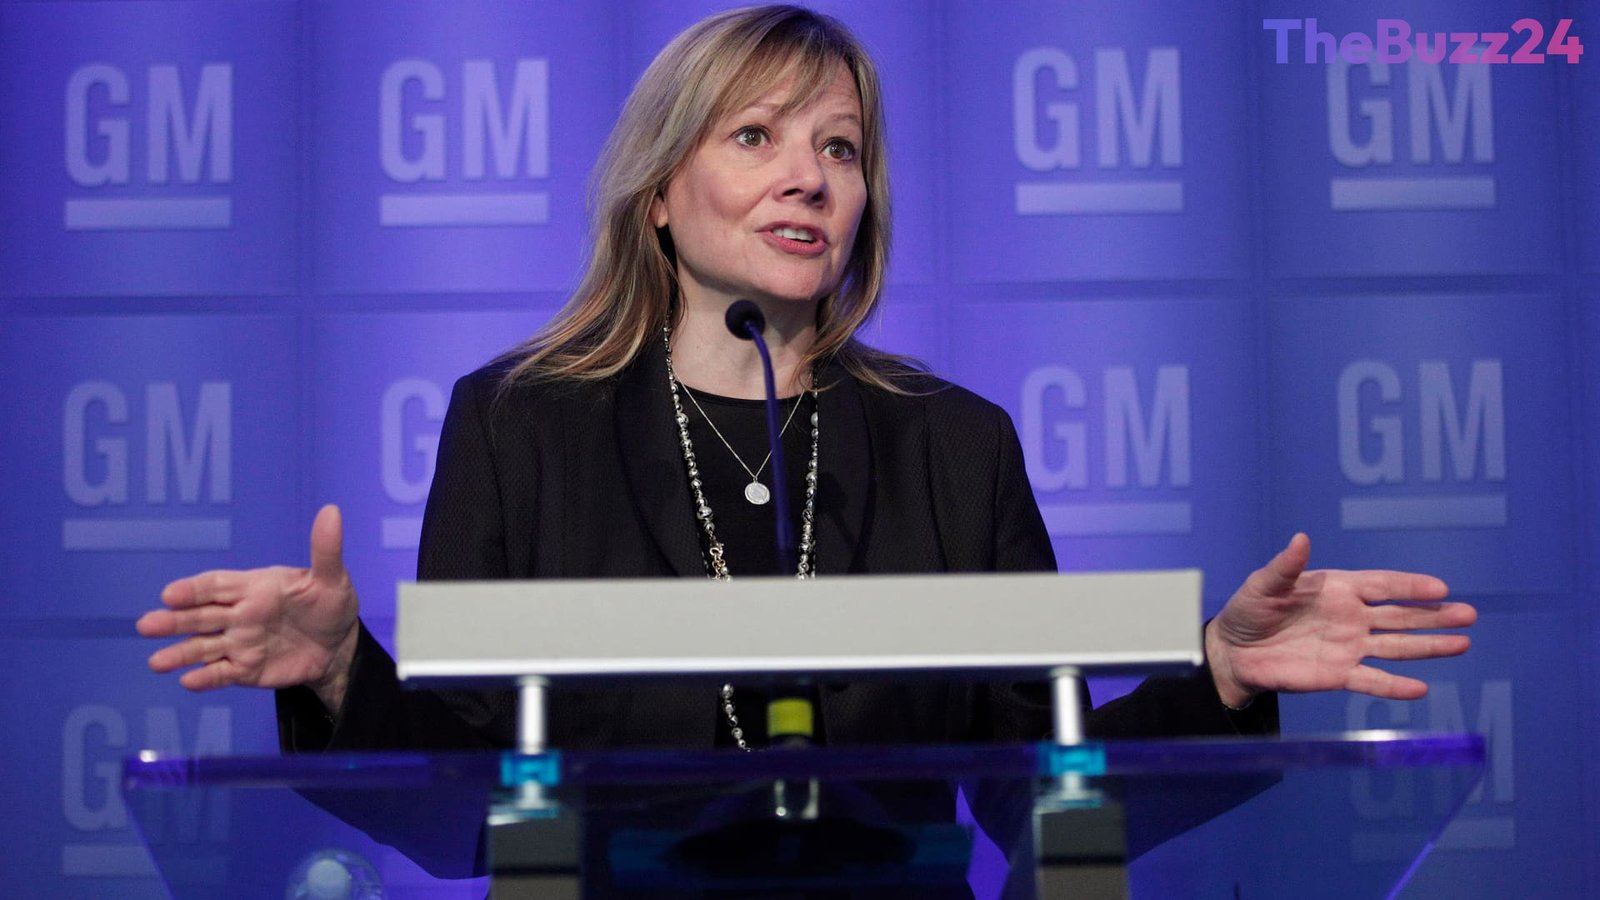
General Motors delivered an impressive third-quarter financial performance, topping market estimates on both revenue and net income, fueled by persistent strength across its North American automotive operations. The Detroit automaker posted quarterly revenue of $50.02 billion, exceeding consensus expectations of $48.7 billion. Net income attributable to stockholders reached $3.3 billion, marking a substantial jump of nearly $2 billion compared to the same period last year.
Capitalizing on its solid operational execution, the company announced an ambitious new multi-year stock repurchase authorization of $20 billion. The sizable capital return program follows the completion of an earlier $6 billion share buyback that launched at the start of the year. Alongside the buyback news, GM elevated its automotive free cash flow forecast for the full year, now anticipating between $11.5 billion and $12.5 billion, up significantly from its prior projection of $9.5 billion to $11.5 billion.
Despite the operational beats, company executives narrowed full-year earnings guidance, setting adjusted earnings before interest and taxes (EBIT) at $14.5 billion to $15.5 billion, which translates to an adjusted earnings per share range of $12.75 to $13.75. The updated midpoint of $13.25 per share arrived just below Wall Street’s consensus expectation of $13.41, triggering an initial drop in share price during early trading. Company leadership confirmed that the fourth quarter is poised to see a sequential deceleration as the business confronts year-end cost pressures.
Automotive executives highlighted that GM is effectively managing severe commodity and supply chain headwinds, with inflation costs expected to touch the upper boundary of guidance at roughly $2 billion due to logistics expenses and rising prices for semiconductor memory chips. Meanwhile, the carmaker indicated that the charges associated with recalibrating its electric vehicle transition are now largely behind it, having absorbed $11.2 billion in related costs since late last year. Looking ahead, management aims to preserve pricing discipline and manufacturing efficiency to sustain profitability into the coming fiscal year.
Key Takeaways
- General Motors beat third-quarter expectations with $50.02 billion in revenue and $3.3 billion in net income.
- The automaker authorized a massive $20 billion multi-year share buyback and raised full-year free cash flow guidance up to $12.5 billion.
- A narrowed full-year earnings per share outlook and rising commodity costs sparked cautious sentiment among investors.
Editor’s Analysis & Impact
General Motors’ third-quarter performance illustrates the underlying power of its legacy truck and SUV business in North America, which continues to generate the vast majority of corporate profits. This operational cash engine is enabling GM to fund a massive $20 billion shareholder return while absorbing the multi-billion-dollar costs of dialing back its near-term electric vehicle ambitions. However, the tepid market response to its updated guidance highlights growing Wall Street sensitivity to inflation headwinds. With commodity costs, warranty liabilities, and memory chip prices rising toward the top of guidance, GM’s pricing flexibility will be tested if automotive demand cools. Preserving double-digit margins will hinge on management’s ability to maintain manufacturing efficiency and prevent aggressive vehicle discounting in 2026.
Frequently Asked Questions
Q: Why did GM stock dip despite beating Q3 revenue and earnings expectations?
A: GM shares slipped in early trading because the company's narrowed full-year earnings per share guidance midpoint of $13.25 came in slightly below Wall Street's estimate of $13.41, coupled with warnings of a sequential slowdown in the fourth quarter.
Q: What are the details of General Motors' new share repurchase program?
A: GM announced an open-ended, multi-year $20 billion stock buyback program, which follows the successful completion of an earlier $6 billion repurchase initiative initiated at the start of the year.
Q: What primary cost challenges is GM facing heading into year-end?
A: The automaker is dealing with commodity inflation costs near the top end of its $2 billion guidance range, driven primarily by elevated logistics fees, dynamic random-access memory (DRAM) chip pricing, and elevated warranty expenses.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category