US Housing Market Faces Severe Slump as Interest Rates and Inflation Collide
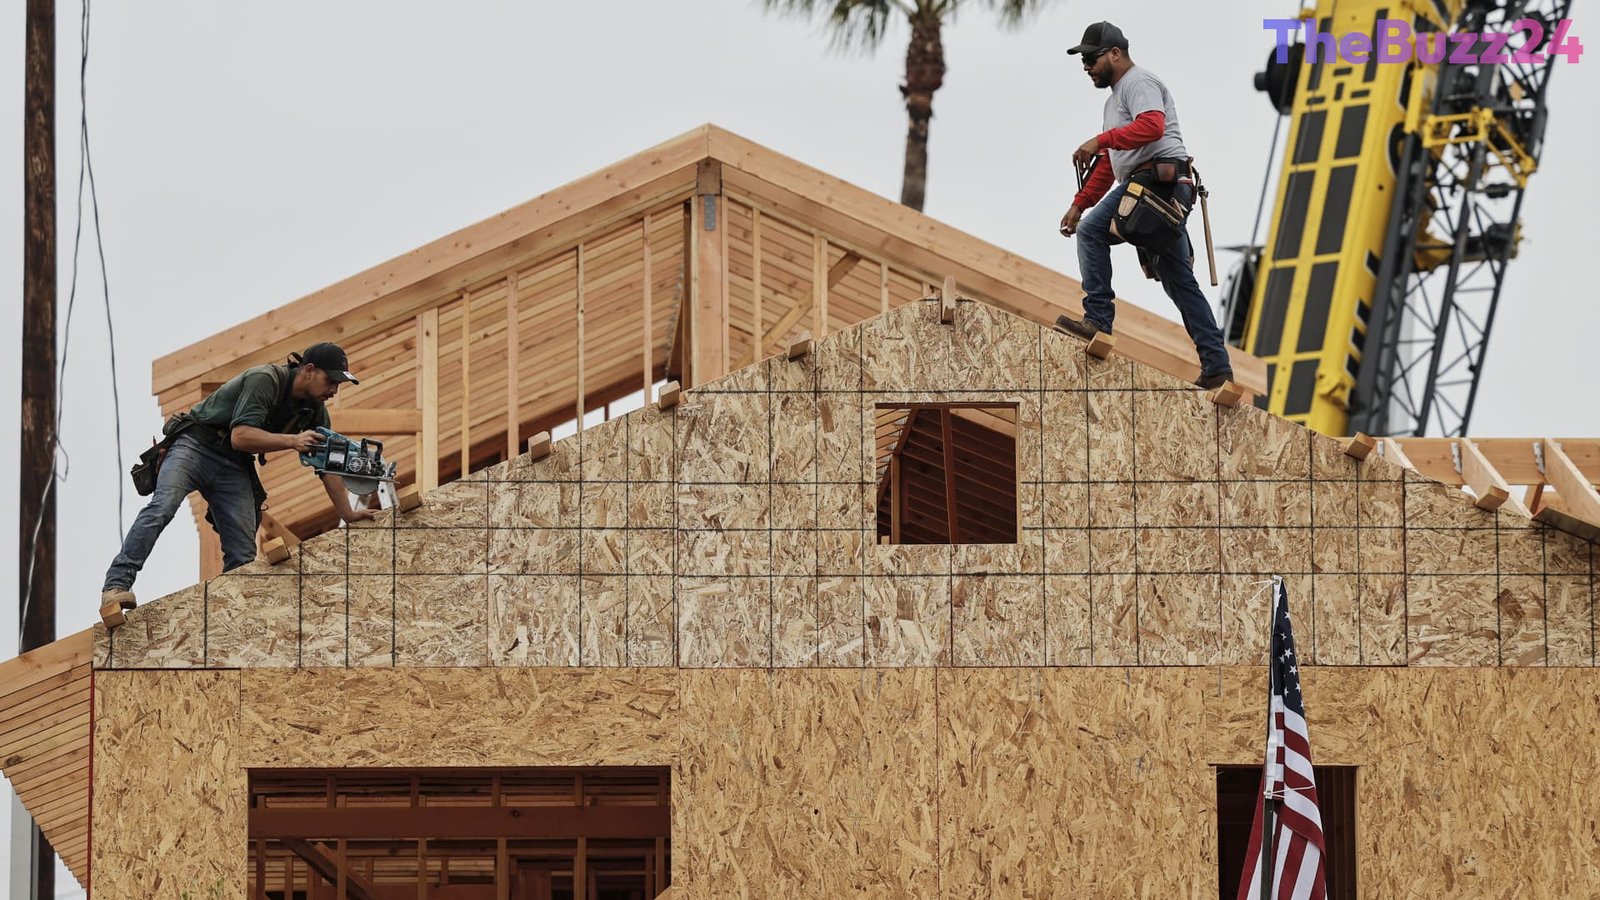
The United States housing market is experiencing a profound downturn, characterized by sharp declines in building permits, housing starts, and pending sales that have significantly underperformed market forecasts. September data highlighted the mounting pressures facing the residential sector, as soaring borrowing costs and persistent inflation create a formidable obstacle course for prospective buyers and developers alike. With average mortgage rates holding stubbornly above historical norms, affordability has plummeted to critical levels, leaving much of the prospective buyer pool sidelined.
Simultaneously, the Federal Reserve finds itself caught in a complex policy dilemma. Typically, a weakening housing sector would prompt the central bank to ease monetary policy to stimulate demand. However, with broader price pressures stubbornly high and inflation remaining the primary target, officials appear inclined to prioritize price stability over rescuing the flagging property market. This stance increases the likelihood of further interest rate adjustments, which could drive mortgage rates even higher and intensify the freeze across the industry.
Compounding these challenges is the entrenched ‘lock-in’ effect, where an overwhelming majority of existing homeowners secured sub-5% mortgages in previous years, discouraging them from selling and taking on significantly higher rates for a new property. Consequently, residential investment and existing home sales are projected to remain depressed for the foreseeable future. While some economists suggest borrowing costs may be nearing their peak, a swift recovery remains unlikely without substantial shifts in macroeconomic policy and a meaningful improvement in housing affordability.
Key Takeaways
- Housing metrics including permits, starts, and pending sales fell significantly below Wall Street forecasts in September.
- The Federal Reserve continues to prioritize combating inflation over easing monetary policy to support the struggling housing market.
- The 'lock-in' effect, driven by existing homeowners holding low mortgage rates, is keeping inventory tight and turnover low.
Editor’s Analysis & Impact
The collision between persistent inflation and a slowing housing market presents a classic macroeconomic headache for central bankers. As mortgage rates remain elevated, the structural shortage of housing inventory is paradoxically locking current owners into their homes while pricing out new buyers. This dynamic limits the transmission mechanism of traditional monetary policy. In the broader industry context, homebuilders are likely to scale back single-family construction, further capping supply and ensuring that affordability remains a chronic issue. Looking forward, the sector faces a prolonged period of stagnation unless broader economic cooling forces a pivot in interest rate trajectories or a dramatic correction in property valuations occurs.
Frequently Asked Questions
Q: Why is the housing market slumping despite potential Fed intervention?
A: The Federal Reserve is currently prioritizing the reduction of persistent inflation over rescuing the housing sector. Even though housing data is deteriorating, central bank officials remain focused on broader price pressures.
Q: What is the 'lock-in' effect in the current housing market?
A: The lock-in effect occurs when a vast majority of existing homeowners hold mortgages with rates significantly lower than current market levels, making them reluctant to sell and take on much more expensive new loans.
Q: How are mortgage rates affecting new construction and pending sales?
A: High mortgage rates have severely reduced home affordability, pushing pending sales to historic lows and causing building permits and housing starts to drop well past analyst expectations.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category