Navigating the ‘Cocktail of Disruption’: How Bain Capital’s Real Estate Strategy is Evolving
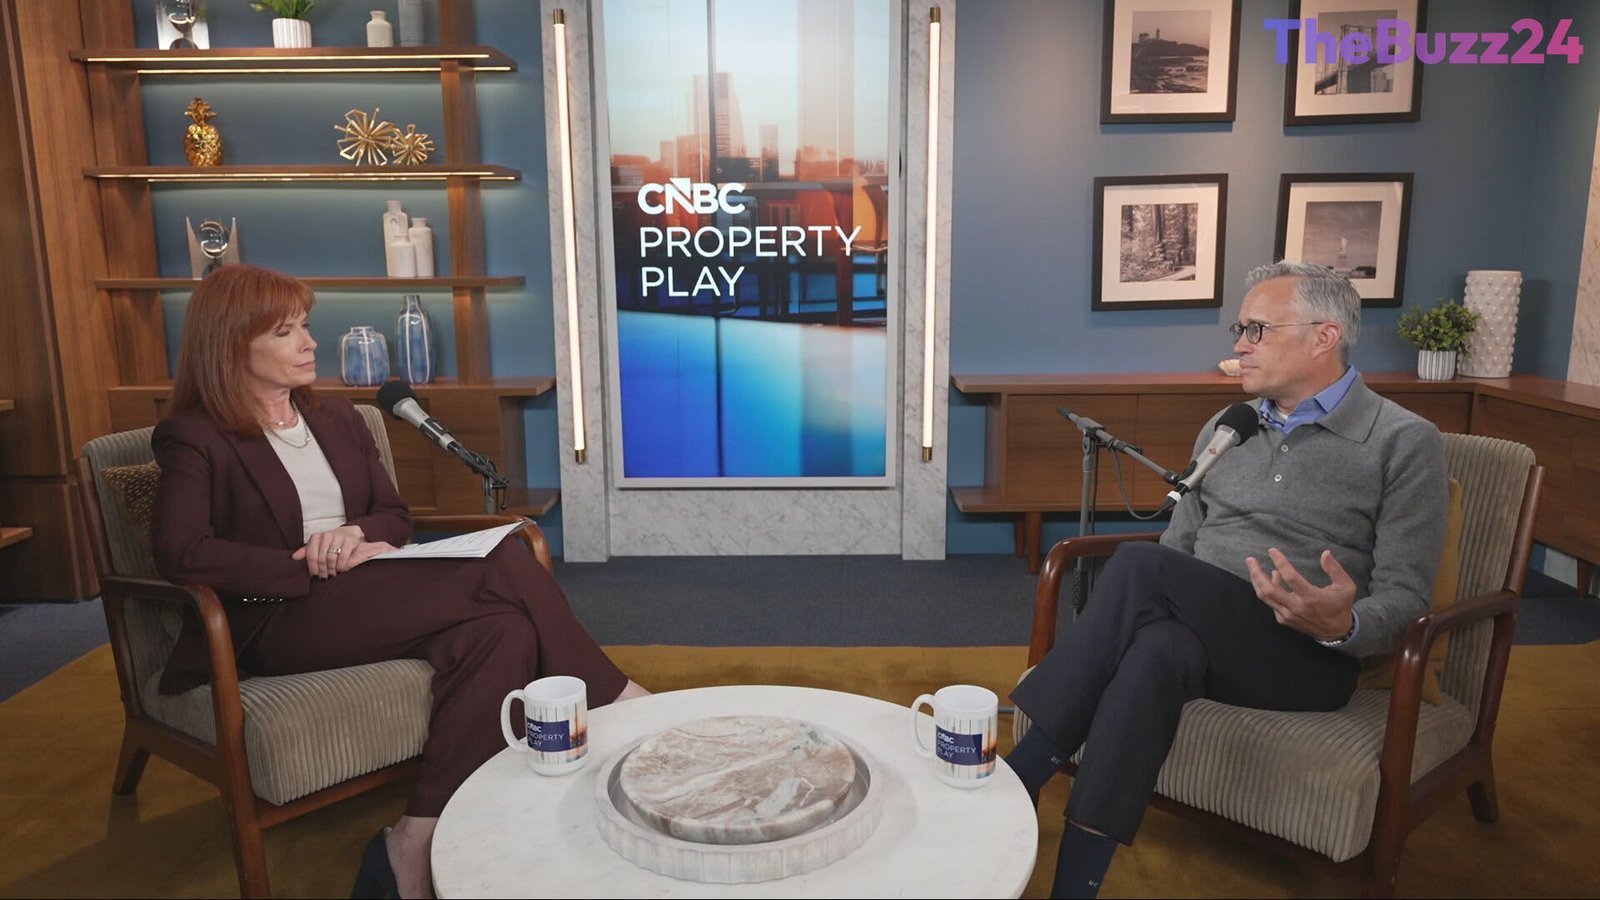
The modern real estate landscape is currently defined by a persistent cycle of macroeconomic shocks that have left many investors struggling to find stability. Ryan Cotton, head of real estate at Bain Capital, describes the current environment as a ‘cocktail of disruption,’ where frequent geopolitical and economic shifts force constant re-evaluations of asset values. This volatility has led to a slowdown in transaction volume, as investors grapple with the difficulty of pricing assets in a market that rarely settles long enough to find a consistent equilibrium.
To combat this uncertainty, Bain Capital has shifted its focus away from traditional real estate sectors—such as standard office spaces, retail malls, and certain oversupplied multifamily markets—toward alternative asset classes. Cotton emphasizes that the firm operates as a long-term investor rather than a short-term trader, evaluating secular demand drivers over a ten-year horizon. This strategic pivot is designed to bypass the structural weaknesses currently plaguing traditional property types, which have seen their share of global investment drop significantly over the last decade.
Instead, the firm is increasingly targeting ‘super alternatives’ that benefit from wealth concentration and supply scarcity. Assets such as private airplane hangars and marinas for yachts have become focal points, as these sectors often provide robust net operating income growth and face significant barriers to new supply. By focusing on these niche areas, investors are finding opportunities that are less correlated with the broader, more volatile economic cycles that continue to impact traditional commercial real estate.
Ultimately, Cotton advocates for a disciplined approach that ignores the short-term emotional swings of the market. By focusing on fundamental value creation and long-term structural trends, investors can remain resilient even when the broader market is in a state of confusion. As capital continues to migrate toward specialized sectors like data centers and senior housing, the definition of a ‘core’ real estate investment is undergoing a permanent transformation.
Key Takeaways
- Frequent macroeconomic shocks are creating a 'cocktail of disruption' that complicates asset valuation and slows transaction volume in the real estate market.
- Bain Capital is shifting capital away from traditional sectors like office and retail toward alternative assets such as private airplane hangars and marinas.
- Long-term investment strategies that focus on secular demand drivers are proving more effective than short-term trading in the current volatile economic climate.
Editor’s Analysis & Impact
The shift described by Bain Capital reflects a broader structural migration in the global real estate market. As traditional asset classes like office space face existential threats from remote work and shifting demographics, institutional capital is aggressively seeking ‘defensive’ alternatives. The move toward luxury-adjacent infrastructure—such as private aviation and marine storage—highlights a trend where wealth concentration creates pockets of demand that are insulated from general economic downturns. This strategy suggests that the future of institutional real estate will be defined by specialization rather than scale in traditional sectors. Investors who fail to adapt to these ‘secular demand drivers’ risk holding stranded assets, while those who pivot toward specialized, supply-constrained niches are likely to capture the next wave of institutional liquidity.
Frequently Asked Questions
Q: What does Ryan Cotton mean by the 'cocktail of disruption'?
A: It refers to the combination of frequent macroeconomic shocks, shifting demand patterns caused by AI and changing work habits, and the lingering oversupply of traditional real estate assets that makes current market valuation difficult.
Q: Why is Bain Capital moving away from traditional real estate sectors?
A: Bain Capital is moving away from sectors like office and retail due to a lack of structural demand drivers and an oversupply of product, opting instead for alternative asset classes that offer better growth potential and scarcity.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category