Saudi East-West Pipeline Disruption Threatens Asian Energy Markets as Refiners Brace for Rising Costs
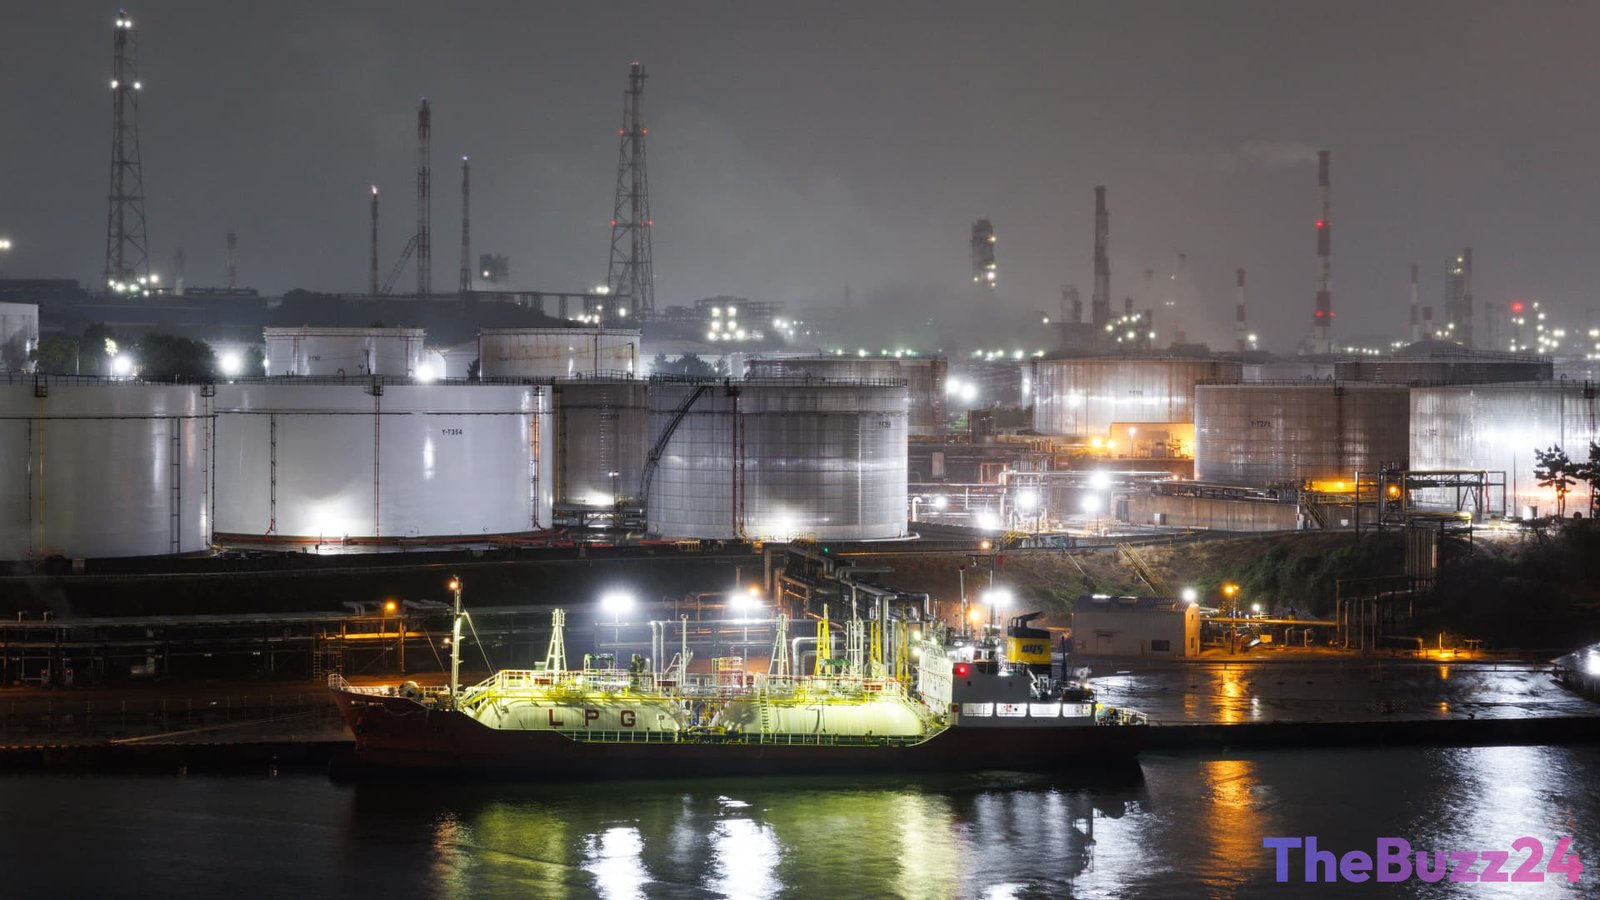
The sudden operational halt of Saudi Arabia’s critical East-West crude pipeline is stoking widespread concerns across Asia’s key energy importers, threatening to squeeze an already tight regional market. With export routes via the Strait of Hormuz previously restricted, substantial Saudi export volumes had been rerouted westward across the Arabian Peninsula to the Red Sea port of Yanbu. The unexpected disruption along this conduit puts an estimated 3.5 million to 4.5 million barrels per day of Asia-bound crude supply in jeopardy once onshore storage reserves are exhausted.
Among the regional economies facing potential fallout, South Korea is notably exposed, as Saudi shipments comprised 34.1% of its overall crude imports in July. Japan follows closely with 27.3% reliance, while China and India draw roughly 14.9% and 10.2% of their respective import volumes from the Kingdom. Although alternative loading facilities in the Persian Gulf and limited storage reserves at Yanbu and in Egypt offer an immediate buffer, market analysts estimate these stockpiles will only sustain regular export flows for approximately one to two weeks.
In the immediate term, market participants anticipate that refiners across Asia will feel the squeeze primarily through inflated spot premiums and escalated freight rates, rather than outright physical shortages. The cost of medium-sour grades is already widening, signaling tightening fundamentals before actual supply deficits emerge on factory floors. While replacing delayed Middle Eastern supplies with cargoes from the Atlantic Basin—such as the Americas or West Africa—remains an option, these substitute shipments typically require upwards of a month to arrive.
Despite the headwinds, energy strategists at institutions like Macquarie highlight that Asian refiners boast greater feedstock flexibility than in previous supply shocks, allowing facilities to process diverse crude grades and pivot dynamically on the spot market. Although official restoration timelines from Riyadh remain undisclosed and industry estimates range from three to six weeks of repair work, U.S. Energy Secretary Chris Wright recently expressed optimism, signaling that the critical conduit could return to active service in the very near future.
Key Takeaways
- The halt of Saudi Arabia's East-West pipeline places between 3.5 million and 4.5 million barrels per day of Asia-bound crude at risk of disruption.
- South Korea and Japan are the most vulnerable Asian buyers, relying on Saudi crude for roughly 34% and 27% of their total imports, respectively.
- Refiners are expected to face an immediate surge in spot premiums and freight expenses, while physical shortages may take weeks to manifest if the shutdown lingers.
Editor’s Analysis & Impact
The closure of the East-West pipeline underscores the fragility of global oil transit corridors in an increasingly turbulent geopolitical climate. While built specifically to bypass the vulnerabilities of the Strait of Hormuz, the reliance on a single trans-peninsular artery shows that alternative logistics carry their own operational risks. Over the coming weeks, the primary danger is not an immediate absence of barrels, but the compounding inflation of refining margins, tanker charter rates, and regional benchmark prices. If repairs extend past a month, Asian refiners will have no choice but to compete aggressively for West African and American barrels, pulling supply away from Atlantic markets and triggering a synchronized global rise in energy costs.
Frequently Asked Questions
Q: Which Asian countries are most impacted by the Saudi pipeline shutdown?
A: South Korea and Japan face the highest proportional risk, with Saudi oil representing roughly 34% and 27% of their total crude imports, respectively. China and India are also exposed, though their import portfolios are somewhat more diversified.
Q: How long can existing oil reserves mitigate the supply gap?
A: Crude held in storage tanks at the Red Sea terminal of Yanbu and in Egypt is estimated to cover standard export volumes for only one to two weeks before shipments drop off significantly.
Q: What is the expected timeline for repairing the East-West pipeline?
A: While Saudi authorities have not provided an official timeline, industry forecasts project repairs could take between three and six weeks, though U.S. officials have indicated the pipeline could resume operations much sooner.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category