Homeowners Hoard Record Wealth: Trillions in Equity Untapped Amid Economic Uncertainty
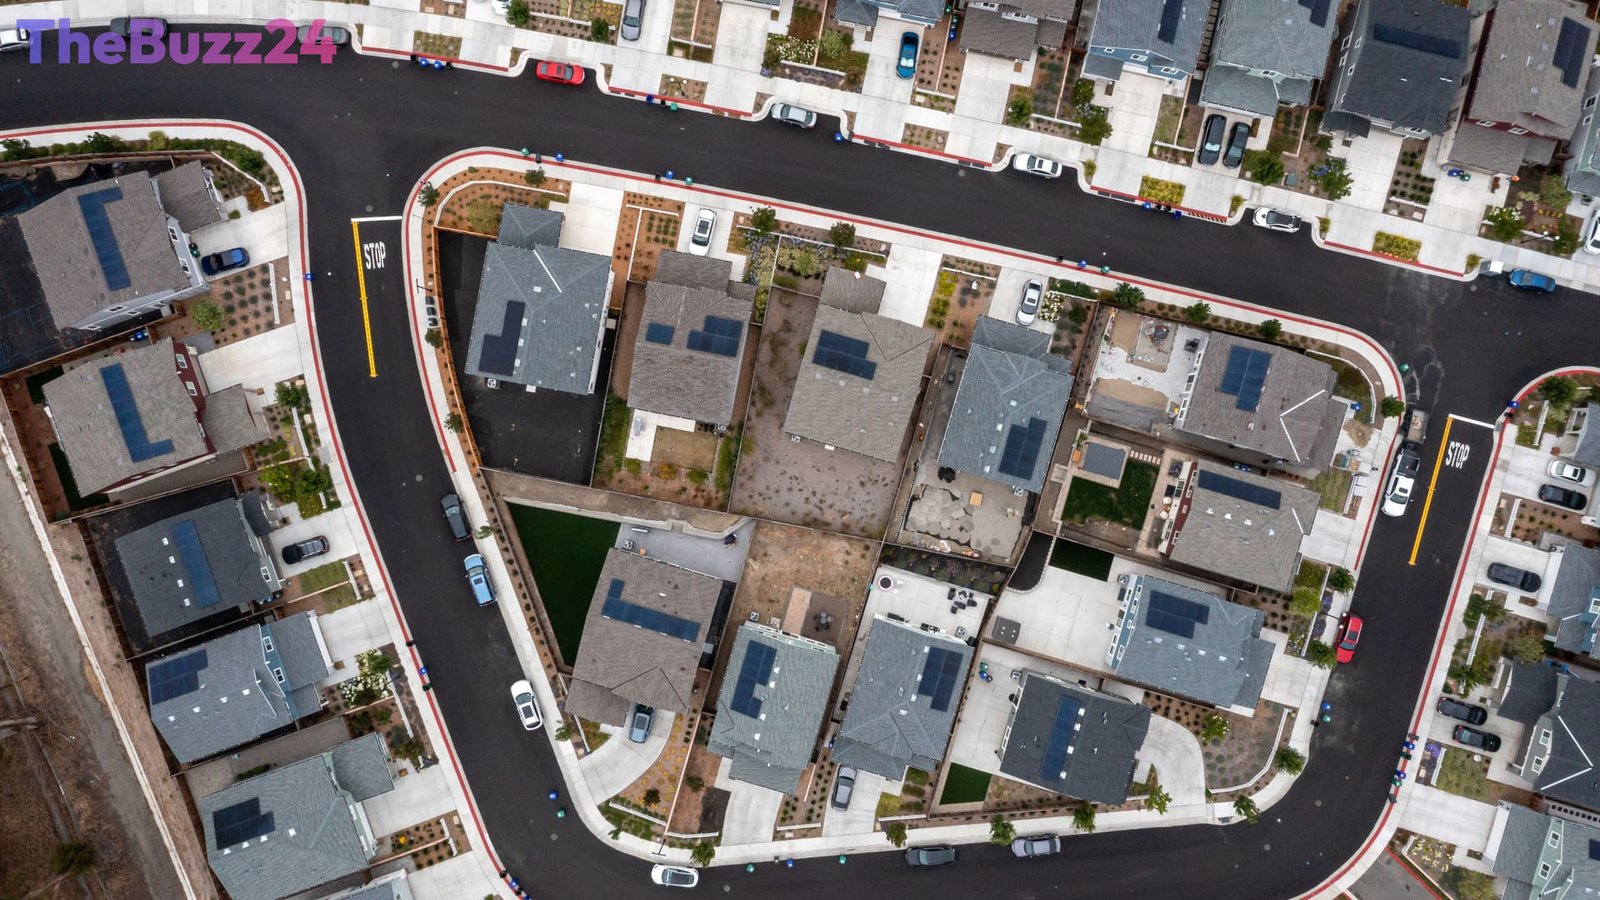
U.S. homeowners are currently sitting on an unprecedented amount of housing wealth, with a staggering $11.5 trillion in “tappable” home equity available as of the second quarter of this year. This substantial financial cushion is a direct result of significant home price appreciation seen over the past few years. However, despite this record level of equity, homeowners are largely choosing not to access these funds.
Experts suggest that homeowners with the most substantial housing wealth are often the least inclined to tap into it. This demographic typically benefits from low mortgage rates secured in recent years, possesses strong personal cash flow, and faces fewer immediate pressures to relocate. Consequently, even though homeowners originated nearly 20% more second mortgages or home equity lines of credit (HELOCs) in the second quarter compared to the first, this activity still represents less than 0.1% of the total available tappable equity.
Several factors contribute to this reluctance to borrow against home equity. The prevailing economic uncertainty and rising interest rates make consumers hesitant. Taking out a new loan, especially a second mortgage, would likely come with a significantly higher interest rate than their existing primary mortgage, a move most homeowners will avoid unless absolutely necessary. Many homeowners who secured mortgages during the pandemic benefited from historically low rates, providing them with ample monthly cash flow to cover expenses like home improvements or educational costs without needing to dip into their home equity.
Geographic variations in home equity are also notable. Homeowners in Western and Northeastern states, such as Hawaii and California, boast the highest average equity levels, exceeding $600,000 and $400,000 respectively. In contrast, states like Louisiana, Oklahoma, and Iowa show average equity levels just above $100,000. This disparity is widening as home price appreciation continues to be stronger in already high-equity markets. While most homeowners are gaining equity, a small percentage, particularly in states like Texas, Minnesota, Colorado, and the District of Columbia, are experiencing declining home values and losing equity, though the overall rate of homeowners owing more than their homes are worth remains low at 2.1%.
Key Takeaways
- U.S. homeowners collectively hold a record $11.5 trillion in tappable home equity.
- Despite record equity, homeowners are largely not accessing these funds due to economic uncertainty and high interest rates.
- Significant regional disparities exist in home equity levels, with Western and Northeastern states leading.
Editor’s Analysis & Impact
The current situation presents a fascinating paradox in the housing market: immense wealth locked up in home equity, yet a pronounced reluctance to utilize it. This trend underscores a heightened sense of caution among consumers, likely driven by inflation, rising interest rates, and broader economic anxieties. The low utilization of tappable equity suggests that homeowners are prioritizing financial stability and avoiding costly debt, especially when their primary mortgages are secured at historically low rates. This could impact sectors reliant on consumer spending for home improvements or major purchases. The widening equity gap between regions may also exacerbate existing economic disparities. As interest rates potentially stabilize or decline in the future, we might see a gradual increase in equity tapping, but for now, homeowners appear to be playing it safe.
Frequently Asked Questions
Q: What is "tappable" home equity?
A: Tappable home equity refers to the portion of a homeowner's equity that can be borrowed against without exceeding a certain loan-to-value ratio, typically set by lenders to ensure they maintain a comfortable equity cushion. It's the amount of equity a homeowner could potentially access through loans like home equity loans or HELOCs.
Q: Why are homeowners hesitant to use their home equity?
A: Homeowners are hesitant due to economic uncertainty, rising interest rates making borrowing more expensive, and the desire to maintain low payments on their primary mortgages secured at lower rates. Many also have sufficient cash flow from other sources to cover expenses.
Q: Are all homeowners seeing their equity increase?
A: No, while most homeowners have seen their equity increase due to rising home prices, some areas are experiencing declining home values. This has led to a loss of equity for homeowners in specific regions like parts of Texas, Minnesota, Colorado, and the District of Columbia.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category