Homebuyers Retreat as Mortgage Rates Surge to Highest Levels Since Late 2023
The housing market is facing severe headwinds as mortgage interest rates climbed for the sixth consecutive week, reaching heights not seen since November 2023. This relentless upward trajectory has pushed overall mortgage demand down to its lowest level in two years. Prospective buyers and homeowners looking to refinance are pulling back rapidly as the cost of borrowing continues to erode purchasing power.
According to industry data, the average contract interest rate for a standard 30-year fixed-rate mortgage with conforming loan balances ($832,750 or less) jumped to 7.30%, up from 7.12% the prior week. For those seeking immediate market pricing, daily averages spiked even higher, touching 7.58% recently. This surge has severely impacted the refinancing sector, with weekly refinance applications plunging 9%—a staggering 56% drop compared to the same period last year. Government-backed refinancing options, including FHA and VA loans, also experienced double-digit declines.
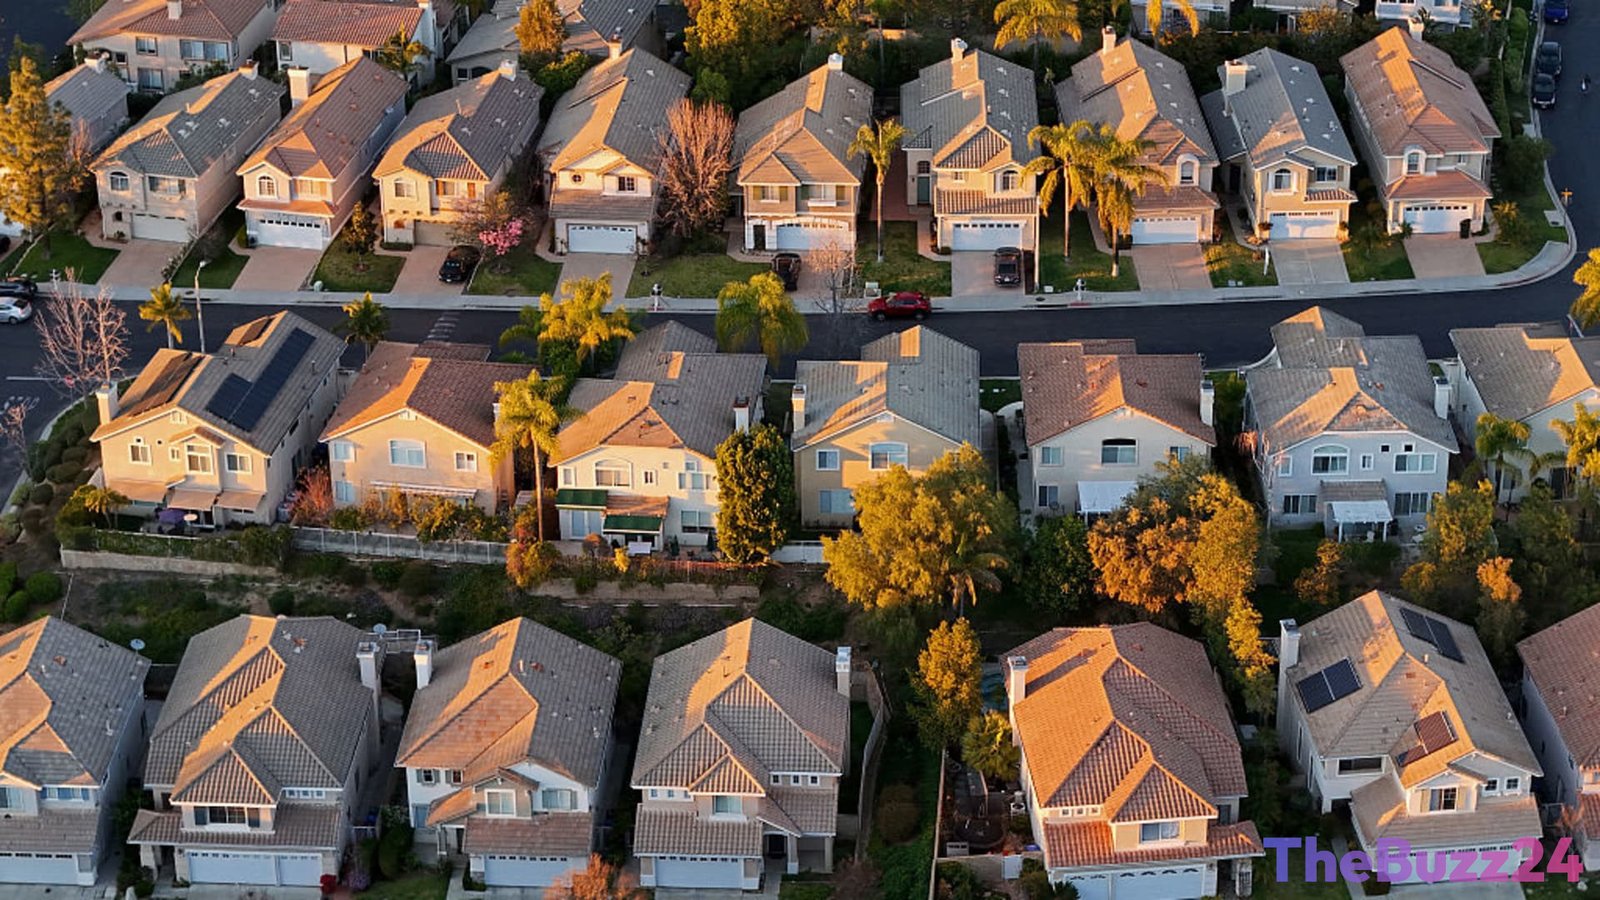
The purchase market is feeling the squeeze as well, with home purchase applications falling 4% weekly and 14% year-over-year. Compounding the issue of high interest rates is the persistent rise in home prices. The S&P CoreLogic Case-Shiller index indicated that national home prices rose 1.9% annually in July, accelerating from a 1.6% gain in June. In an effort to find financial relief, an increasing number of buyers are turning to riskier adjustable-rate mortgages (ARMs), which currently offer rates roughly 80 basis points lower than fixed-rate options. ARMs recently accounted for 10.3% of all applications, marking their highest share since late 2023.
Financial analysts attribute the ongoing rate surge to broader macroeconomic shifts. The bond market is actively adjusting to changing expectations surrounding Federal Reserve monetary policy, persistent inflation, and resilient economic growth. Despite occasional relief in other sectors, such as fluctuating oil prices, mortgage rates remain heavily tied to bond yields, leaving little hope for immediate relief for hopeful American homebuyers.
Key Takeaways
- Mortgage rates have risen for six consecutive weeks, with daily averages for 30-year fixed loans reaching 7.58%, the highest level since November 2023.
- Overall mortgage demand has plummeted to a two-year low, driven by a 56% year-over-year drop in refinancing applications and a 14% decline in purchase applications.
- Rising home prices and high rates are pushing buyers toward adjustable-rate mortgages (ARMs), which now make up over 10% of all applications.
Editor’s Analysis & Impact
The current surge in mortgage rates highlights a challenging paradox in the U.S. housing market: despite cratering demand, home prices continue to rise due to severely limited inventory. The bond market’s recalibration of Federal Reserve policy expectations suggests that high rates are here to stay for the medium term. As inflation remains sticky and economic growth persists, the central bank is unlikely to rush into aggressive rate cuts. This environment will continue to freeze the housing market, as current homeowners with low locked-in rates refuse to sell, and prospective buyers are priced out. The growing popularity of adjustable-rate mortgages (ARMs) indicates consumer desperation, but it also introduces systemic risk if rates remain elevated when these loans reset. Expect the housing sector to remain in a state of stagnation until macroeconomic indicators signal a definitive cooling of the economy.
Frequently Asked Questions
Q: Why are mortgage rates continuing to rise?
A: Mortgage rates are rising primarily because the bond market is adjusting to expectations of prolonged high interest rates from the Federal Reserve, driven by persistent inflation and steady economic growth.
Q: What is an adjustable-rate mortgage (ARM), and why are buyers choosing them now?
A: An ARM is a mortgage with an interest rate that changes periodically after an initial fixed period. Buyers are choosing them now because their initial rates are currently about 0.80% lower than standard fixed-rate mortgages, offering short-term affordability.
Q: How has the rate hike affected home refinancing?
A: Refinancing activity has collapsed, dropping 56% compared to last year, because very few existing homeowners can find a lower rate than what they currently have locked in.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category