China’s Industrial Engine Restarts: Manufacturing PMI Snaps Contraction Streak in September
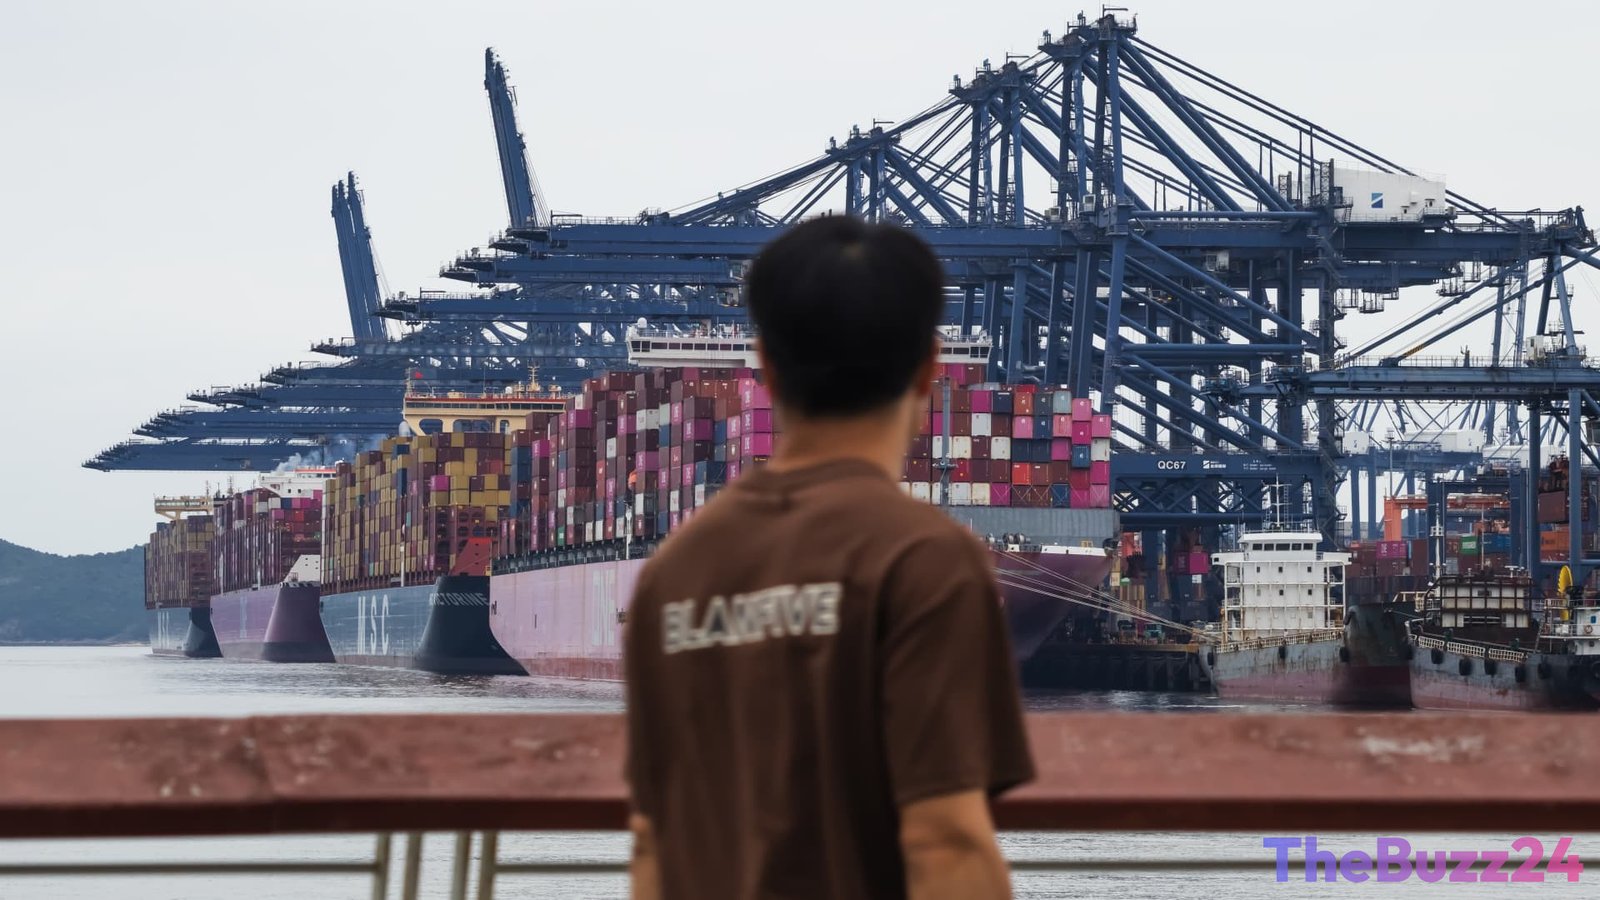
China’s industrial sector showed signs of recovery in September, breaking a consecutive two-month contractionary streak. The official manufacturing purchasing managers’ index (PMI) edged up to 50.1 from 49.8 in August, signaling a return to expansionary territory. This turnaround aligns with recent efforts by Beijing to inject fresh momentum into an economy struggling with domestic demand and a prolonged property downturn.
According to data from the National Bureau of Statistics, the modest expansion was primarily propelled by accelerated activity in high-tech manufacturing, equipment production, and consumer goods. Additionally, the non-manufacturing PMI climbed to 50.2, indicating a parallel recovery in the services and construction sectors. While the global boom in artificial intelligence hardware has provided a significant tailwind for Chinese manufacturers, rising energy costs linked to geopolitical tensions in the Middle East continue to squeeze profit margins.
In response to persistent economic headwinds, Chinese policymakers recently unveiled a suite of targeted fiscal and monetary interventions. The People’s Bank of China expanded lending support programs for infrastructure and technology, while also lowering interest rates to ease borrowing costs. Concurrently, the finance ministry introduced temporary mortgage subsidies for qualified first-time homebuyers. However, financial analysts remain divided on the efficacy of these measures. Some experts characterize the policy package as a “mini stimulus” designed to do just enough to secure the government’s annual growth target of 4.5% to 5%, rather than spark a robust, long-term economic revival.
Despite these interventions, structural challenges persist. While exports have remained a vital pillar of economic support this year, growing pushback from international trading partners over excess manufacturing capacity threatens this revenue stream. Analysts at Goldman Sachs noted that while the new mortgage subsidies may temporarily boost housing transactions, strict eligibility criteria will likely limit their broader macroeconomic impact. Consequently, the focus remains on how effectively these supply-side credit easing policies are implemented in the coming quarters.
Key Takeaways
- China's official manufacturing PMI rose to 50.1 in September, signaling a return to expansion after two months of contraction.
- Beijing introduced targeted monetary and fiscal stimulus, including mortgage subsidies and expanded bank lending, to stabilize the economy.
- While high-tech manufacturing and exports remain strong, weak domestic consumption and international trade tensions pose ongoing challenges.
Editor’s Analysis & Impact
The marginal rebound in China’s manufacturing PMI to 50.1 offers a temporary sigh of relief for global markets, but it highlights a deeply fragmented recovery. Beijing’s latest “mini stimulus” is highly targeted, focusing on supply-side credit easing and modest housing subsidies. While this may suffice to nudge GDP growth toward the official 4.5% to 5% target for the year, it stops short of the aggressive demand-side bazooka needed to cure deep-seated consumer anxiety and the real estate crisis. Furthermore, China’s heavy reliance on exports to offset weak domestic demand is hitting a wall of rising protectionism from Western trading partners. Investors should expect continued volatility, as sustainable long-term growth will require more comprehensive structural reforms rather than incremental credit injections.
Frequently Asked Questions
Q: What does a PMI reading above 50 indicate?
A: A Purchasing Managers' Index (PMI) reading above 50 indicates expansion in the sector compared to the previous month, while a reading below 50 signals contraction.
Q: What specific stimulus measures did China introduce in September?
A: The measures included expanded lending quotas from the People's Bank of China for infrastructure and technology, reduced interest rates, and temporary mortgage subsidies for eligible first-time homebuyers.
Q: Why are analysts skeptical about the long-term impact of these policies?
A: Many economists view the measures as a "mini stimulus" that primarily supports the supply side and housing market on a limited scale, rather than addressing the core issues of weak domestic consumer demand and systemic property market weakness.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category