Empowering Gen Alpha: How Today’s Youth Are Building Early Wealth and Financial Literacy
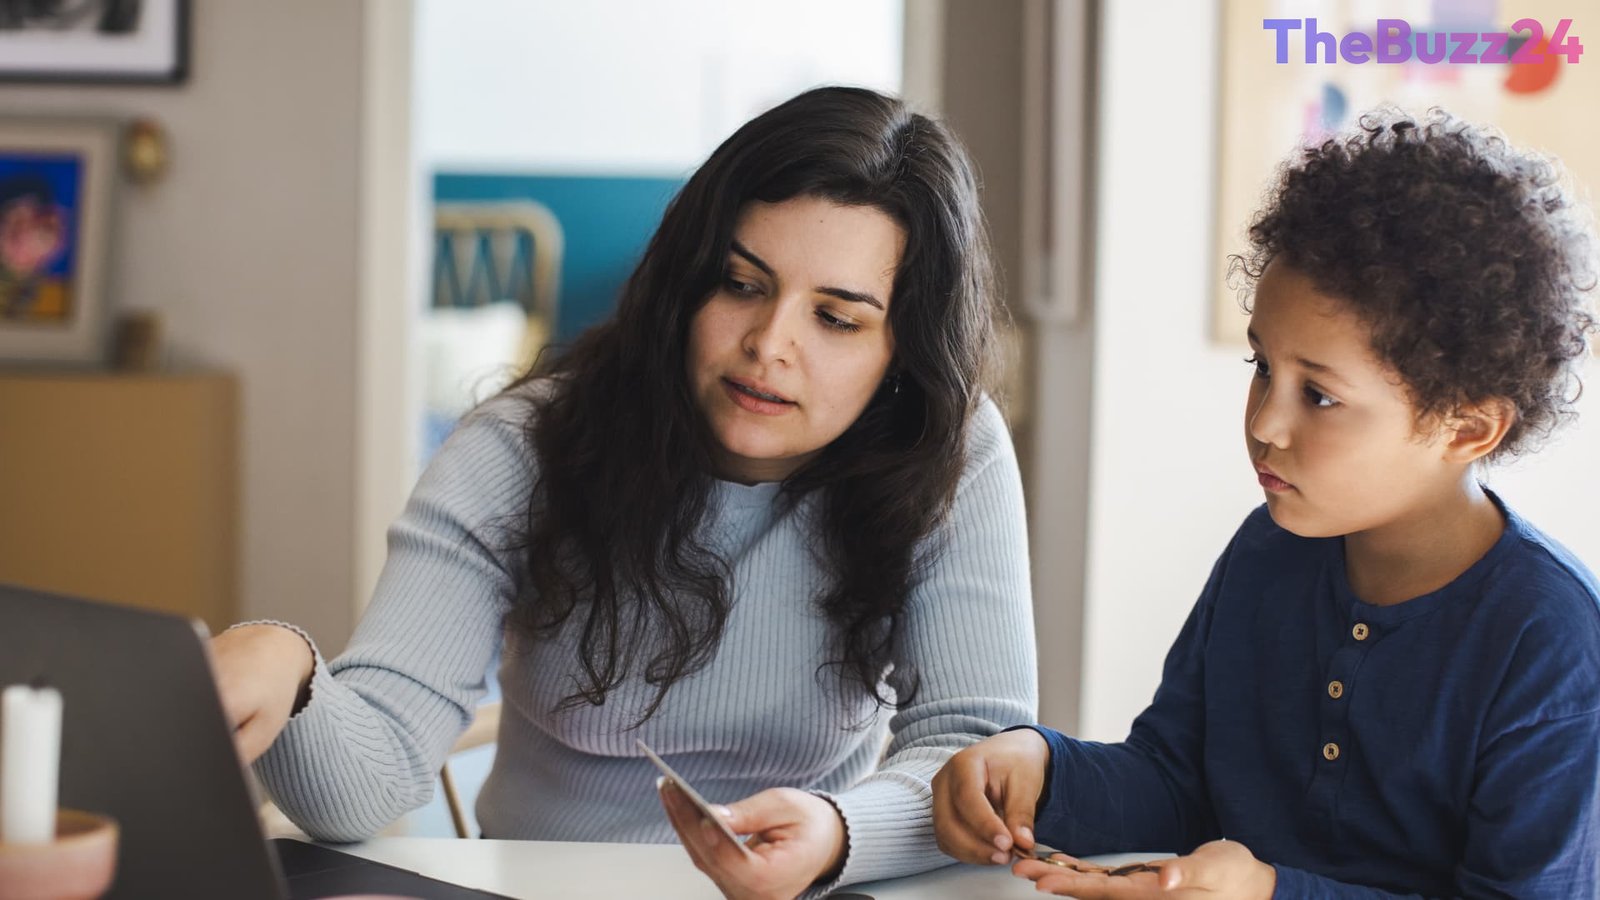
A growing number of children and adolescents are stepping into the financial world much earlier than previous generations. Recent data highlights that an overwhelming majority of kids between the ages of 7 and 14 possess their own financial resources, often accumulated through creative entrepreneurial endeavors such as neighborhood stands, online resale markets, chores, and digital gigs. While many youngsters quickly figure out how to spend their hard-earned cash on daily treats or trending consumer products, a parallel trend shows a strong inclination toward saving, investing, and planning for long-term goals.
Financial experts emphasize that cultivating robust money habits during childhood lays a crucial foundation for future economic stability. Because minors cannot independently open financial accounts, parental guidance plays an instrumental role in bridging the gap between earning and strategic wealth-building. Families have access to a diverse array of financial instruments tailored for youth, ranging from standard joint savings accounts and high-yield vehicles to specialized educational funding plans and custodial brokerage accounts.
Platforms designed specifically for younger demographics have also emerged, offering kid-friendly mobile interfaces where children can actively propose trades or monitor their savings progress under parental supervision. Educational initiatives, both in traditional classrooms and through specialized youth advisory boards, are demystifying concepts like the stock market and compound interest. By normalizing open conversations about budgeting, trade-offs, and financial consequences, parents can effectively steer the next generation toward enduring financial independence.
Key Takeaways
- A vast majority of children aged 7 to 14 currently manage their own money, driven largely by entrepreneurial activities and online resale markets.
- Parents play a vital role in establishing financial security by utilizing tools like custodial accounts, joint savings, and educational investment plans.
- Early financial education significantly reduces the intimidation surrounding concepts like the stock market and compound interest for young earners.
Editor’s Analysis & Impact
The rise of financially active Gen Alpha youth marks a paradigm shift in how consumer habits and wealth management education begin. As digital platforms lower the barrier to entry for micro-entrepreneurship and online resale, children are encountering concepts of capital allocation and risk much earlier in life. This trend has profound implications for the fintech and banking sectors, prompting institutions to develop specialized, guardrailed products aimed at younger demographics and their parents. Looking forward, the mainstream integration of personal finance into youth culture could drastically alter broader market dynamics, creating a more financially literate consumer base entering the workforce over the next decade. Financial technology companies that successfully gamify and secure these early savings habits are likely to secure long-term brand loyalty as these young earners mature into high-net-worth adults.
Frequently Asked Questions
Q: What tools can parents use to help children invest?
A: Parents can utilize several tools including custodial brokerage accounts (UTMA/UGMA), 529 educational savings plans, custodial IRAs for earned income, and specialized apps offered by financial platforms that require parental approval for trades.
Q: At what age do most children start earning and managing their own money?
A: Surveys indicate that children as young as 7 up to age 14 frequently manage their own funds through allowances, odd jobs, entrepreneurship, and online marketplaces, with the vast majority making independent spending decisions.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category