French Markets Reel as Civil Unrest and Mounting Debt Deepen Fiscal Crisis
Financial markets in France experienced a sharp downturn as widespread social unrest compounded existing anxieties surrounding the nation’s political stability and fiscal health. Government bond yields surged, the euro weakened, and Paris-listed equities faced heavy selling pressure. The turbulence reflects growing investor skepticism regarding the government’s ability to implement necessary fiscal reforms and successfully navigate upcoming budgetary challenges.
The benchmark 10-year French bond yield climbed significantly, pushing borrowing costs to levels not seen in decades. This upward trajectory widened the yield spread between French OATs and German Bunds to its widest margin since the European sovereign debt crisis. Meanwhile, the CAC 40 index underperformed broader European peers, weighed down by political volatility and concerns over how fiscal tightening might impact corporate profitability and consumer spending.
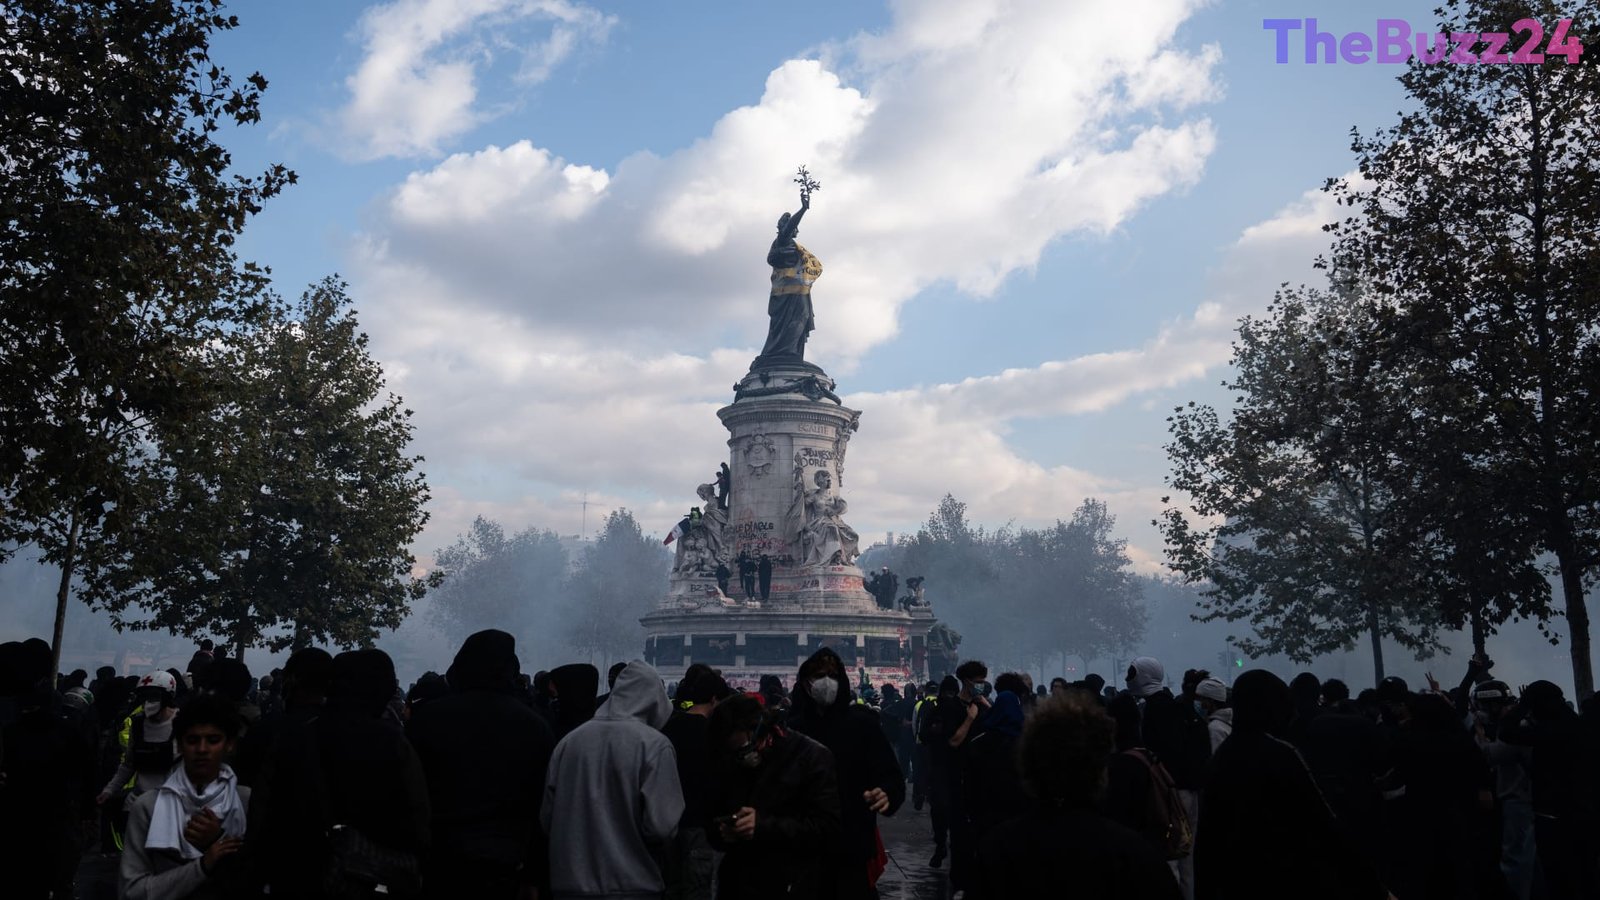
The market jitters follow a weekend of mass demonstrations across major French cities, where hundreds of thousands protested against political paralysis, the rising cost of living, and deteriorating public services. The protests, which resulted in widespread property damage and thousands of arrests, underscore the severe public resistance to any measures aimed at curbing the national deficit. International investors are increasingly wary of a scenario where the government is caught between mounting market pressure to reduce debt and intense social backlash against austerity.
Prime Minister’s minority administration faces a daunting path ahead as it attempts to negotiate the upcoming budget against a backdrop of legislative gridlock and shifting political polling. Analysts warn that without credible fiscal consolidation plans—such as spending cuts or tax increases—France risks entering a persistent debt spiral. While some experts note that underlying demand for French debt remains intact for now, the escalating tension between market demands and social stability highlights a precarious future for the eurozone’s second-largest economy.
Key Takeaways
- French government bond yields spiked dramatically, pushing borrowing costs to multi-decade highs amid growing political and fiscal uncertainty.
- Widespread weekend protests and civil unrest across major French cities added to investor anxiety over the nation's governability and economic stability.
- The widening yield spread between French and German bonds reflects deepening skepticism regarding the government's ability to reduce its deficit and pass upcoming budgets.
Editor’s Analysis & Impact
The unfolding fiscal and political crisis in France serves as a critical stress test for the eurozone’s financial architecture. As borrowing costs escalate and social unrest paralyzes legislative agendas, the nation finds itself trapped between the demands of bond markets for strict fiscal consolidation and the political reality of fierce public resistance to austerity. This dynamic threatens to strain the credibility of French sovereign debt, potentially forcing the European Central Bank into politically sensitive interventions if market liquidity is severely disrupted. For international investors, the situation underscores the vulnerability of major European economies to domestic political fragmentation and rising populist sentiment, likely keeping volatility elevated across European equities and fixed-income assets for the foreseeable future.
Frequently Asked Questions
Q: Why are French bond yields rising?
A: French bond yields are rising due to mounting political instability, concerns over the country's growing national deficit, and widespread civil unrest that complicates the government's ability to implement fiscal reforms.
Q: What is the OAT-Bund spread and why does it matter?
A: The OAT-Bund spread is the difference in yield between French government bonds (OATs) and German federal bonds (Bunds). A widening spread indicates that investors view French debt as riskier, leading to higher borrowing costs for the French government and local corporations.
Q: Could the European Central Bank intervene in the French debt crisis?
A: While analysts suggest the European Central Bank would prefer to avoid intervention, it could utilize mechanisms like the Transmission Protection Instrument if market liquidity is severely threatened, though this would likely require strict fiscal commitments from France.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category