Prime Minister Sanae Takaichi Rebuffs Blame Over Plummeting Yen and Escalating Japanese Bond Yields
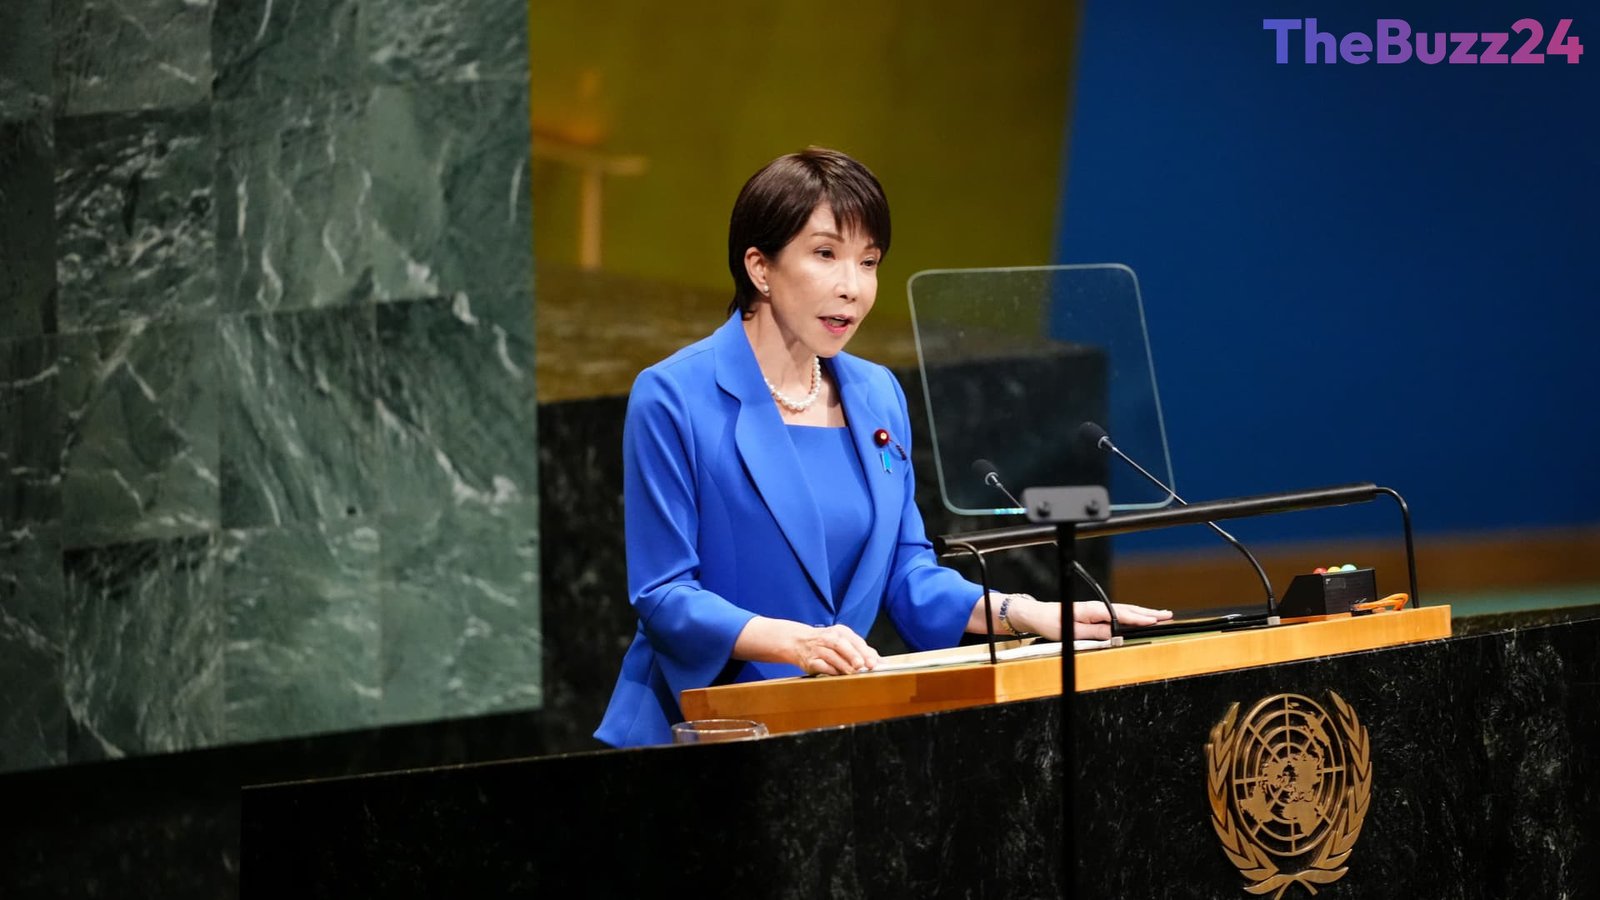
Japanese Prime Minister Sanae Takaichi has mounted a firm defense of her economic agenda, dismissing accusations that her fiscal strategies are responsible for the severe depreciation of the yen or the surging domestic bond yields. Addressing lawmakers in parliament during a debate initiated by opposition representative Yoshifumi Hamano regarding a secondary supplementary budget, Takaichi rejected the notions of a policy-induced weak yen and surging interest rates. She emphasized that establishing fundamental macroeconomic resilience remains the primary vehicle for reviving international confidence in the Japanese currency.
Japan has grappled with intense financial volatility under Takaichi’s administration. The yen has slid to levels not seen since 1986, compelling financial authorities in Tokyo and foreign partners to intervene directly in foreign exchange markets. Concurrently, long-term Japanese government bond yields have climbed to multi-decade peaks as the central bank normalizes monetary policy through interest rate adjustments. While a softer currency traditionally enhances export competitiveness and buffers against international trade pressures, it has also amplified domestic inflation concerns by drastically elevating import expenses.
Fiscal discipline remains a critical point of friction as Takaichi pursues tax relief initiatives, including proposals to reduce sales levies on food alongside supplementary government expenditures. Despite official assurances that sovereign bond issuance for the 2026 calendar year will adhere strictly to baseline budgetary targets, market analysts express skepticism. Financial analysts point out that sustained public spending without corresponding revenue growth inevitably places upward pressure on debt issuance, leaving Tokyo in a precarious position as it attempts to stimulate the economy while containing market-driven bond yields.
Key Takeaways
- Prime Minister Sanae Takaichi denied responsibility for Japan's weakening yen and surging government bond yields during parliamentary debate.
- The administration insists that building a resilient economy and managing debt issuance will restore currency stability, despite past foreign exchange interventions.
- Market analysts remain skeptical of plans to fund supplementary budgets and food tax reductions without increasing government borrowing.
Editor’s Analysis & Impact
Japan stands at a delicate economic crossroads as it navigates the end of ultra-loose monetary policy while wrestling with significant currency vulnerabilities. Prime Minister Takaichi faces the arduous task of easing household cost-of-living pressures through targeted tax reductions without exacerbating the national debt burden. With sovereign yields at multi-decade highs, the cost of servicing Japan’s expansive debt load will inevitably rise, narrowing the government’s fiscal headroom. Furthermore, an excessively depreciated currency risks entrenching imported inflation and eroding consumer purchasing power. Tokyo must convincingly demonstrate that its budget plans can balance public stimulus with fiscal prudence to avert deeper bond market distress and sustain economic stability.
Frequently Asked Questions
Q: Why has the Japanese yen experienced substantial depreciation?
A: The yen has faced downward pressure largely due to wide interest rate differentials between Japan and other major global economies, alongside broader economic shifts, despite recent initial rate hikes by the central bank.
Q: What impact do rising Japanese government bond yields have on the country?
A: Surging yields increase the cost for the government to service its national debt, while also pushing up private lending benchmarks, corporate borrowing expenses, and mortgage rates across the wider economy.
Q: How does the administration plan to pay for supplementary budgets without expanding debt?
A: Prime Minister Takaichi maintains that total bond issuance will stay within original budget caps and that sustained economic expansion will generate the necessary stability to support targeted tax relief and spending measures.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category