France Dodges Credit Downgrade as Moody’s Holds Rating at Aa3 Amid Fiscal and Political Strain
Moody’s has maintained France’s sovereign credit rating at Aa3, preserving its high-grade designation despite deepening political polarization, widespread civic unrest, and surging borrowing costs across the eurozone’s second-largest economy. The credit rating agency nevertheless left its outlook on France at negative, warning that persistent political fragmentation continues to threaten the effectiveness of the country’s key legislative bodies.
The decision arrives against a backdrop of severe fiscal stress for Paris. France’s 10-year government bond yield recently exceeded 5% for the first time since 2002, driving the yield spread against benchmark German bunds to a 15-year peak. With France’s budget deficit sitting at approximately 5.5% of GDP—significantly above the European Union’s 3% ceiling—the nation faces more than $1 trillion in maturing debt by the end of the decade. Government forecasts indicate that public debt could reach 121.7% of GDP by 2027.
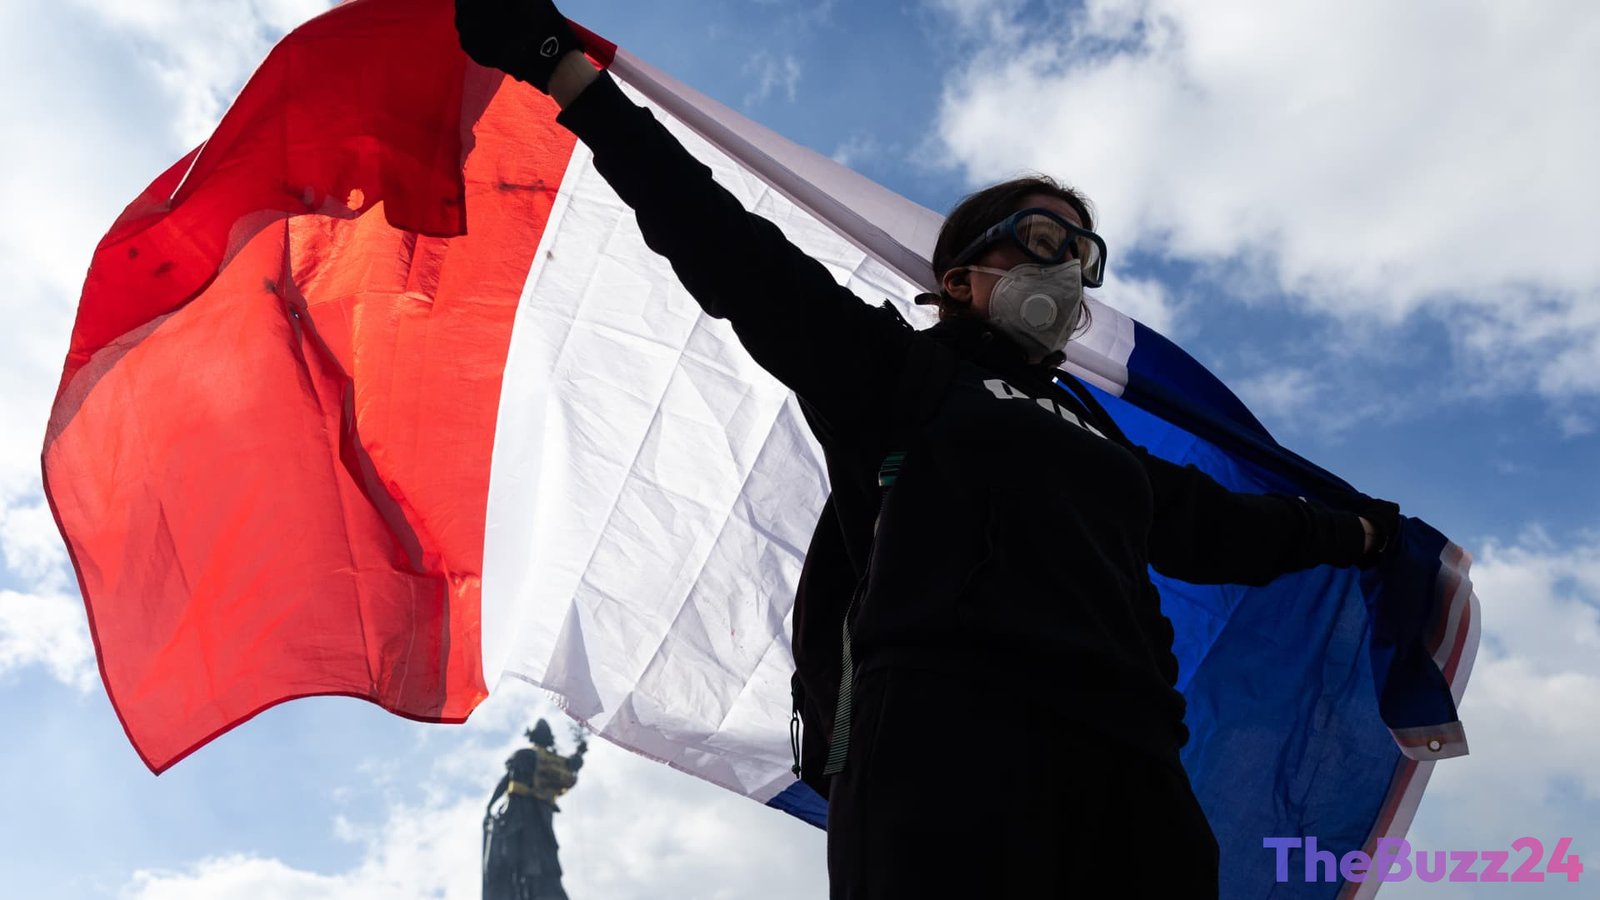
Compounding the fiscal numbers is widespread domestic upheaval. More than half a million citizens recently demonstrated nationwide, voicing anger over escalating living costs and the decline of public infrastructure. The ongoing friction poses major risks to the implementation of structural economic reforms, directly challenging the government’s ability to lower its deficit and manage rising debt-servicing obligations.
While rivals S&P Global and Fitch lowered their respective French ratings in 2025, Moody’s pause grants temporary respite for the French treasury. However, the agency cautioned that returning France’s sovereign outlook to stable will depend entirely on the legislative branch’s ability to reach consensus on credible fiscal consolidation and sustained deficit reduction.
Key Takeaways
- Moody’s kept France's sovereign credit rating at Aa3 but retained a negative outlook, citing deep legislative fragmentation.
- French 10-year government bond yields surged past 5% for the first time since 2002 as the debt spread with Germany widened to a 15-year high.
- France struggles with a budget deficit of 5.5% of GDP and faces projections of public debt climbing to 121.7% by 2027 amid widespread public protests.
Editor’s Analysis & Impact
Moody’s restraint offers short-term breathing room for European debt markets, yet underlying sovereign vulnerabilities in France remain severe. Yields crossing the 5% threshold reflect persistent institutional skepticism regarding Paris’s capacity to rein in spending. With over $1 trillion in obligations maturing by 2030 and a national debt ratio marching toward 122%, debt servicing will increasingly squeeze public budgets. Compounding this challenge is a fractured parliament that drastically diminishes the political viability of aggressive budget austerity. Unless French policymakers overcome deep ideological stalemates to introduce credible deficit reduction, a rating downgrade appears almost inevitable within the next rating cycle, which could rattle European sovereign markets and structurally lift borrowing costs across the continent.
Frequently Asked Questions
Q: Why did Moody's maintain a negative outlook on France?
A: Moody's retained the negative outlook due to fears that France's fragmented political landscape will prevent lawmakers from enacting effective fiscal policies to rein in high deficits and soaring national debt.
Q: What is the current status of France's borrowing costs?
A: France's 10-year government bond yields climbed past 5% for the first time since 2002, widening the risk premium compared to German bunds to its highest level in 15 years.
Q: Have other credit rating agencies downgraded France?
A: Yes, both S&P Global and Fitch reduced their sovereign credit ratings for France earlier in 2025 amid deteriorating public finances.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category