Why Oil Service Stocks May Be the Next Big Opportunity Amid Energy Market Volatility
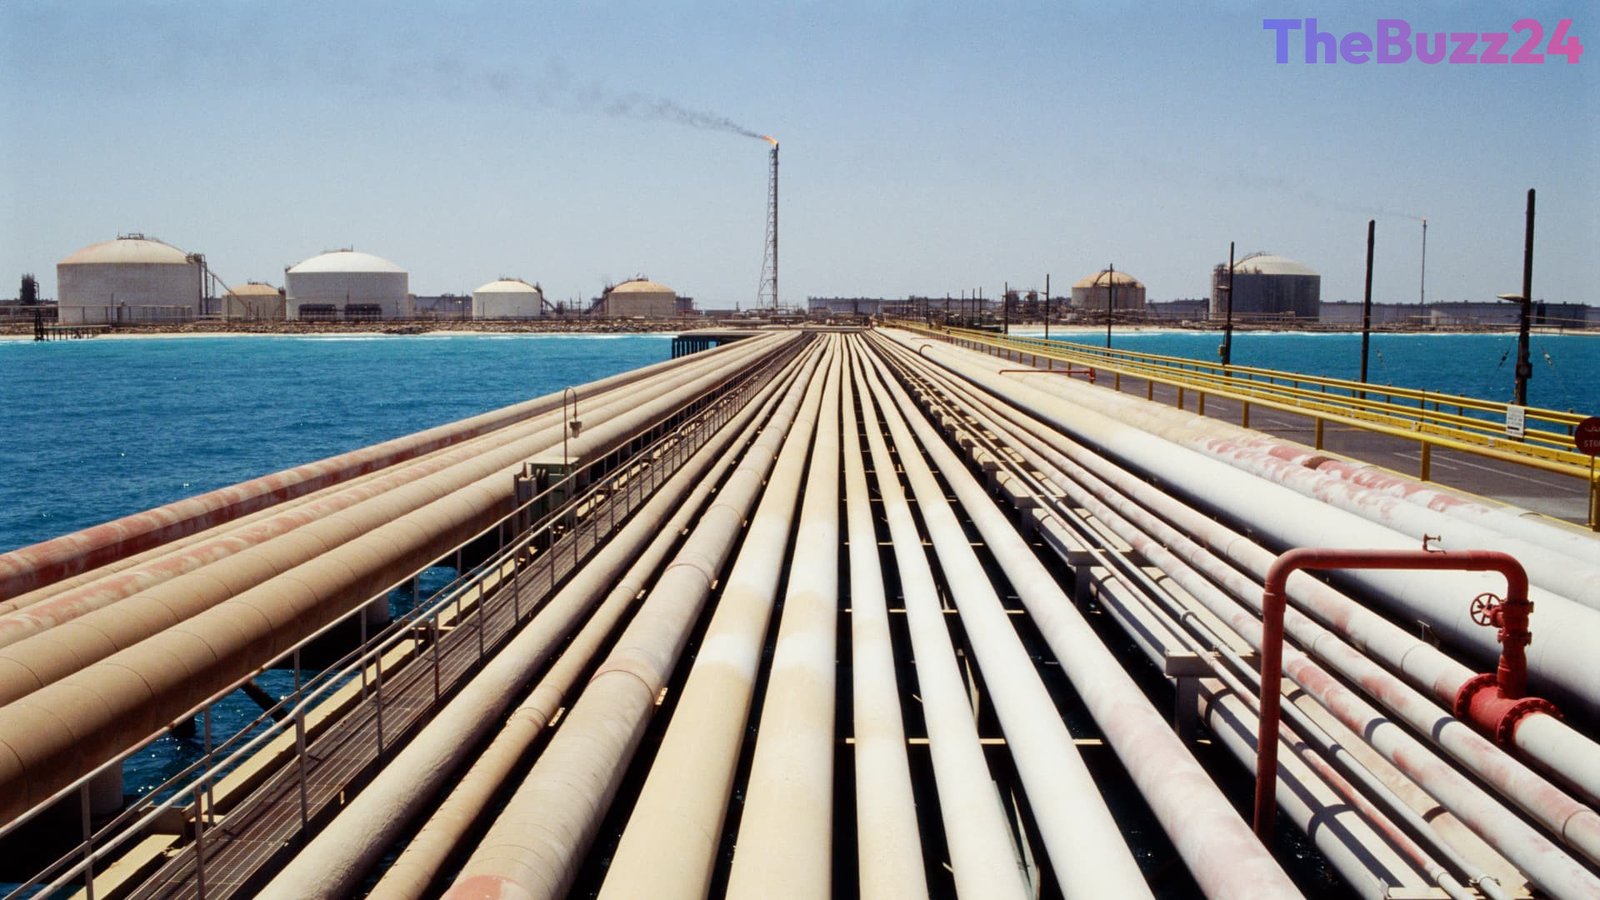
The global energy landscape is undergoing a profound shift as geopolitical instability and supply constraints force a reevaluation of market fundamentals. With oil accounting for 40% of global energy production and nearly all transportation fuel, the complexity of the supply chain—from extraction to refining—has become a focal point for investors. Recent disruptions, including regional conflicts in the Middle East and ongoing geopolitical tensions, have exposed the fragility of global energy security, leading to a sustained bullish trend in oil prices.
While refining companies have enjoyed record-breaking margins due to wide crack spreads, market analysts suggest that the focus may be shifting toward oil service providers. As oil companies look to increase production to meet global demand, the capital expenditure directed toward drilling and infrastructure is expected to rise significantly. This trend mirrors the investment patterns seen in the technology sector, where companies are pouring resources into AI-related infrastructure, positioning oil service firms as critical beneficiaries of the current energy cycle.
Industry experts note that years of underinvestment in mature fields have left spare capacity at historically low levels. Monetary policy adjustments are unlikely to solve these structural supply issues, making increased investment in production capacity essential. Among the major players in this space, SLB stands out as a primary candidate for investors looking to gain exposure to the sector’s growth, particularly through sophisticated options strategies that balance long-term potential with short-term volatility management.
Key Takeaways
- Geopolitical instability and supply chain constraints are driving a sustained bullish trend in global oil markets.
- Refining margins have reached record highs, but future growth is increasingly tied to oil service companies that support production expansion.
- Structural underinvestment in oil fields suggests that supply issues will persist, necessitating long-term capital expenditure in the energy sector.
Editor’s Analysis & Impact
The energy sector is currently navigating a transition from a period of capital discipline to one of necessary expansion. The market’s realization that monetary policy cannot substitute for physical energy supply is a critical turning point for investors. As refining capacity eventually catches up to demand, the focus will likely shift toward the ‘picks and shovels’ of the oil industry—the service providers. The outlook for oil service firms is robust, provided that geopolitical risks do not escalate into total supply chain paralysis. Investors should monitor capital expenditure trends among major oil producers, as these figures serve as a leading indicator for the health and profitability of service-oriented firms like SLB. The broader implication is a long-term revaluation of energy infrastructure as a strategic asset rather than a commodity-dependent utility.
Frequently Asked Questions
Q: Why are oil service companies considered a good investment right now?
A: Oil service companies are expected to benefit from increased capital expenditure as oil producers seek to boost production to address supply shortages and declining mature fields.
Q: What is a 'crack spread' in the context of oil refining?
A: A crack spread refers to the difference between the price of crude oil and the price of the refined petroleum products (like gasoline or diesel) produced from it, representing the refiner's profit margin.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category