Iconic Strand Bookstore Settles $1.5 Million PPP Loan Dispute
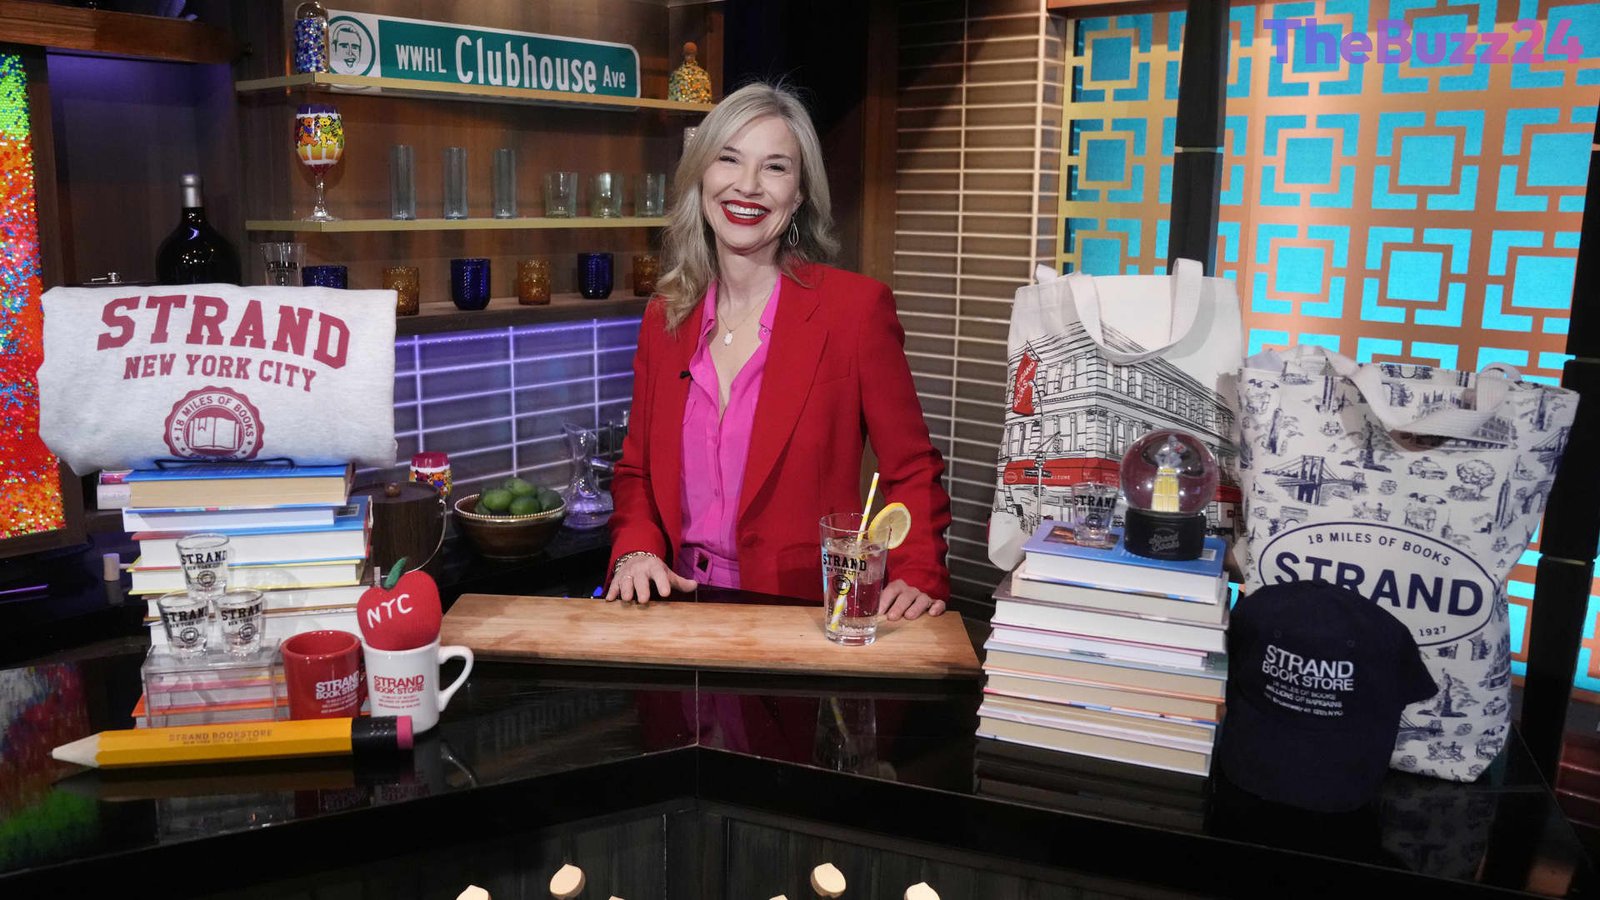
The Strand, a historic New York City bookstore, has reached a civil settlement agreement to pay nearly $1.5 million following allegations that it improperly obtained a government-backed pandemic relief loan. The dispute centered on a $932,350 Paycheck Protection Program (PPP) loan secured by the business in February 2021. Authorities alleged that the bookstore was ineligible for these specific funds because its owner, Nancy Bass Wyden, is the spouse of a sitting U.S. Senator, a status that triggered a statutory prohibition on second-draw PPP loans.
According to federal prosecutors, the loan application included a certification stating that no spouse of a Member of Congress held a controlling interest in the applicant. Officials argued that this certification was materially false, rendering the bookstore ineligible for the financial assistance. While the settlement requires the bookstore to pay $1,482,560, the agreement does not constitute an admission of liability by the company. The case originated from a qui tam lawsuit filed by a private entity known as Blockquote Inc., which is entitled to a portion of the settlement proceeds.
In response to the settlement, representatives for the bookstore characterized the error as unintentional. The company stated that the restriction on spousal ownership was a late addition to the legislative framework of the PPP, and that both the store’s accounting team and the lending institution were unaware of the change at the time of the application. The bookstore emphasized that the oversight occurred during the chaotic environment of the public health emergency and maintained that the business acted without malicious intent. A spokesperson for Senator Ron Wyden noted that the Senator had no involvement in the loan application or the subsequent legal proceedings.
Key Takeaways
- The Strand bookstore agreed to a $1.48 million settlement to resolve allegations of violating PPP loan eligibility rules.
- The violation involved a prohibition against businesses owned by spouses of Members of Congress receiving second-draw pandemic relief funds.
- The bookstore maintains the error was an unintentional oversight by its accounting team and the lending bank during a period of rapidly changing regulations.
Editor’s Analysis & Impact
This settlement highlights the ongoing scrutiny surrounding the distribution of pandemic-era relief funds and the rigorous enforcement of the False Claims Act. By utilizing qui tam lawsuits, the government continues to incentivize private whistleblowers to identify potential fraud or regulatory non-compliance, even in cases where the entity claims the error was administrative rather than malicious. For businesses, this case serves as a stark reminder of the importance of strict compliance monitoring, particularly when dealing with government-backed financial programs that are subject to evolving legislative amendments. The political optics of the case—involving the spouse of a high-profile legislator—underscore the heightened sensitivity and public interest surrounding the allocation of taxpayer-funded relief, suggesting that future audits of such programs will likely remain thorough and unforgiving regarding technical eligibility requirements.
Frequently Asked Questions
Q: Why was the Strand bookstore ineligible for the PPP loan?
A: The bookstore was ineligible because it received a 'second draw' PPP loan, which was prohibited by law for businesses where a spouse of a Member of Congress holds a controlling interest.
Q: Did the Strand admit to wrongdoing in the settlement?
A: No, the settlement agreement specifically states that there was no determination of liability by the store, and the bookstore maintains that the error was unintentional.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category