US Job Growth Expected to Remain Muted as Demographic Shifts Reshape the Labor Market
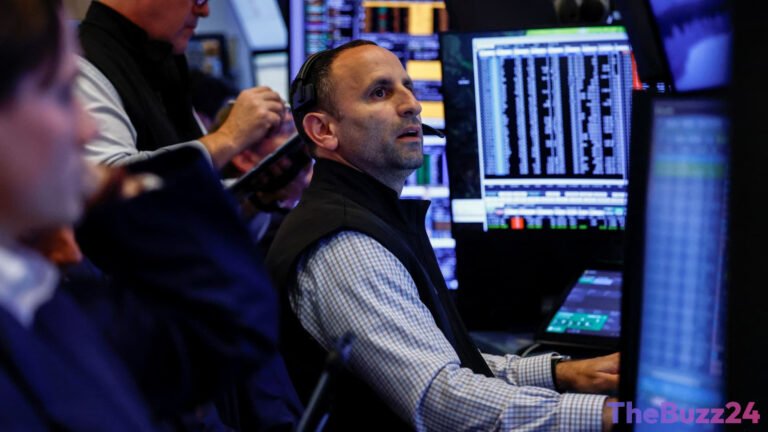
The U.S. labor market is expected to demonstrate modest job creation in October, with standard forecasts pointing toward a modest gain of 59,000 nonfarm payrolls. Despite the muted hiring momentum, the national unemployment rate is projected to remain steady at 4.2%. This dynamic highlights a unique economic landscape where companies are cautious about expanding headcount, yet simultaneously reluctant to initiate widespread layoffs.
The underlying driver of this lower-volume growth environment stems largely from structural labor supply constraints. Demographic shifts, including an aging workforce transitioning into retirement and reduced immigration figures, have effectively shrunk the pool of available workers. Because the overall labor force participation rate has pulled back, the economy no longer requires massive monthly payroll expansions to keep the headline unemployment rate balanced.
While hiring activity has decelerated significantly from post-pandemic highs, several metrics still display underlying resilience. Initial weekly jobless claims have hovered near historic lows, confirming that corporate downsizing remains minimal. Additionally, job openings and voluntary quits have shown recent upticks, signaling that currently employed individuals feel secure in the labor market. However, long-term unemployment has expanded, making it increasingly difficult for out-of-work job seekers to secure new positions amid reduced employer turnover.
Key Takeaways
- October nonfarm payrolls are projected to rise by 59,000, with the unemployment rate holding steady at 4.2%.
- A shrinking overall labor force driven by retirements and lower immigration reduces the need for large monthly job additions to maintain low unemployment.
- Layoffs remain near historical lows, but rising long-term unemployment presents challenges for job seekers trying to re-enter the workforce.
Editor’s Analysis & Impact
The U.S. labor market is undergoing a structural transformation where modest payroll gains no longer indicate economic distress. With labor supply constraints anchored by an aging population, the historical benchmark of needing 200,000-plus job additions per month to maintain equilibrium is evolving. For financial markets and the Federal Reserve, this shift requires a recalibration of how economic health is measured. Rather than focusing solely on top-line payroll figures, analysts must prioritize wage growth, labor force participation, and productivity metrics. The combination of low layoff volume and steady unemployment provides the central bank with flexibility, suggesting the broader economy remains resilient despite slower hiring velocity.
Frequently Asked Questions
Q: What are the job market projections for the upcoming employment report?
A: Forecasts indicate a modest increase of 59,000 nonfarm payroll jobs for October, with the unemployment rate expected to hold at 4.2%.
Q: Why is the unemployment rate remaining low despite slow hiring?
A: The total labor force has contracted due to retirements and demographic changes, meaning fewer total jobs are needed to keep the unemployment rate balanced.
Q: What is the primary challenge for current job seekers?
A: Low employer turnover and modest headcount expansions mean few new roles are being created, leading to an increase in long-term unemployment duration for those without a job.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category