High Stakes Budget Debate Threatens French Government Stability Amid Soaring Debt Costs
French lawmakers are currently grappling with a critical deadline to finalize a national budget by early October, a measure deemed essential to significantly reduce the country’s substantial national deficit. This year’s budget negotiations are unfolding against a backdrop of heightened political tension, with market observers expressing concern that the talks could destabilize the current government, echoing previous periods of political turmoil in Paris.
The financial markets are already reflecting this apprehension. The yield on France’s 10-year government bonds, known as OATs, surged above 4.5% on Friday, marking the first time since 2008, and has since maintained levels around 4.6696%. This increase signifies that France is paying a higher risk premium on its debt, as investors anticipate a third consecutive year of drama surrounding its annual budget. Notably, the yield on French 10-year bonds is now more than one percentage point higher than that of German 10-year bonds, a spread not witnessed since the peak of the euro zone sovereign debt crisis in 2012. Across the G7 group of advanced economies, France is currently facing some of the highest government borrowing costs.
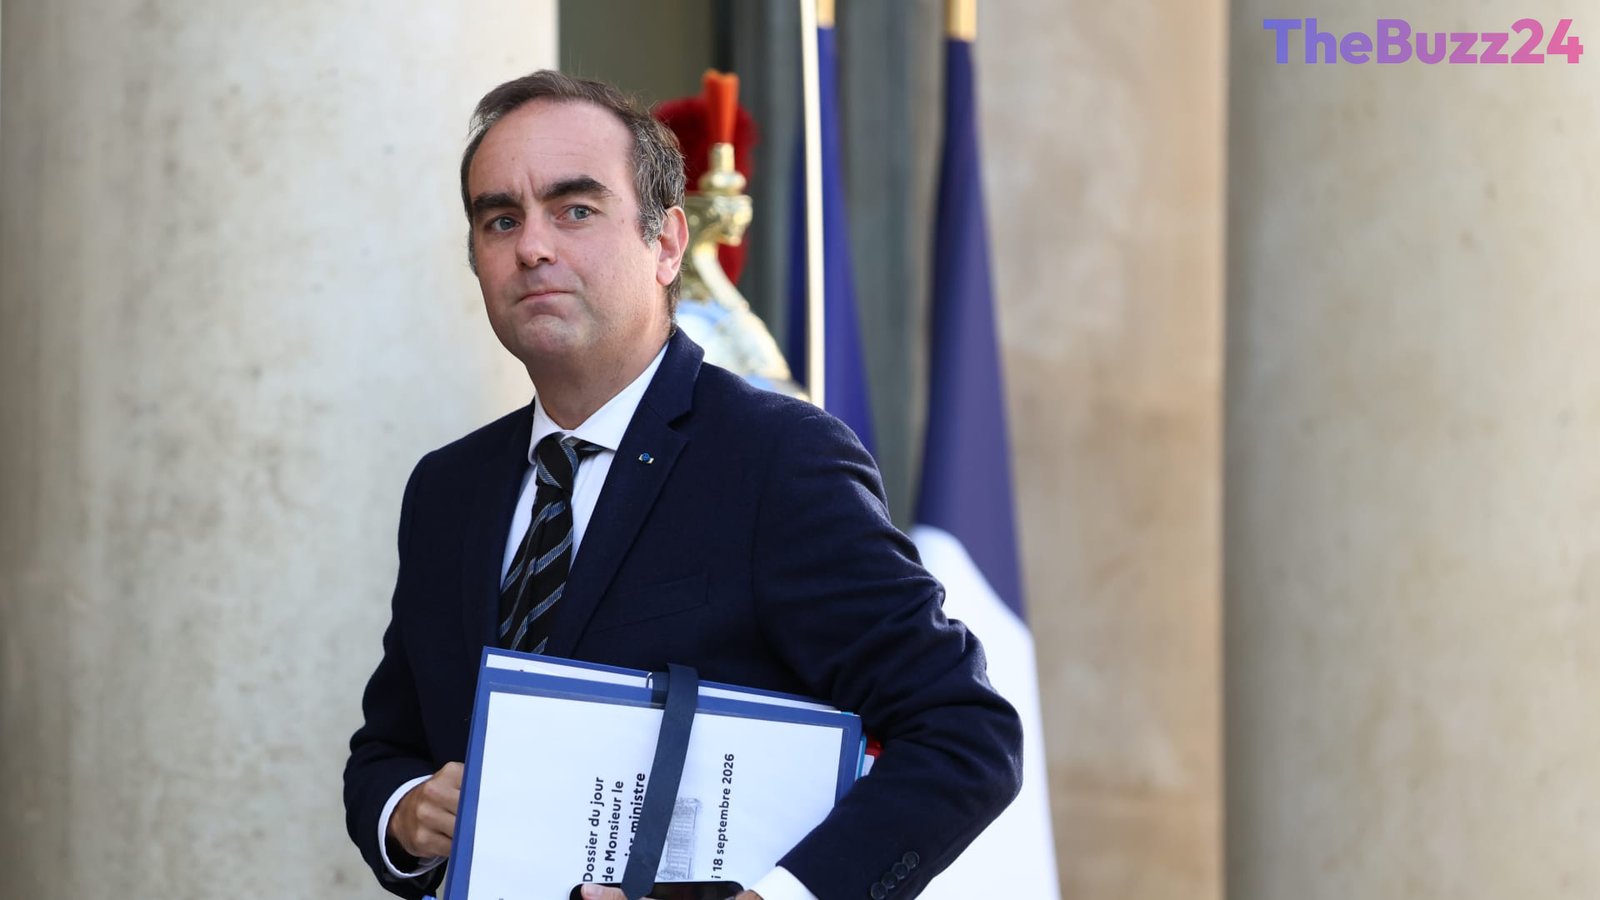
Prime Minister Sébastien Lecornu’s fragile minority government is set to present its draft proposal for the 2027 budget package to parliament in early October. The proposal, which targets 54 billion euros ($61.8 billion) in spending cuts, aims to address France’s ballooning debt load and one of the euro area’s largest budget deficits. The finance ministry projects national debt to reach a record 119.3% of gross domestic product in 2026, climbing to 121.7% in 2027. However, the political landscape, fractured since the July 2024 snap election failed to deliver an absolute parliamentary majority, presents significant challenges. Past administrations have been ousted in no-confidence votes, and Lecornu previously resorted to a constitutional clause to bypass parliament for the 2026 budget.
Experts warn that the proposed 2027 budget, particularly measures like a partial freeze on pensions, will face strong opposition from various parliamentary factions, including the far-right National Rally and the left-wing New Popular Front. Mujtaba Rahman, managing director for Europe at Eurasia Group, suggests that a tough budget risks toppling the government, even as there’s a collective desire to avoid a crisis before next spring’s presidential election. While Lecornu may be determined to push through fiscal reforms, this could necessitate compromises with rival parties or another invocation of special constitutional powers to meet the mid-December deadline. Strategists at ING also highlight that “time is not in favor of French bond spreads,” anticipating continued political headwinds and potential instability stemming from upcoming presidential and legislative elections.
Key Takeaways
- France faces a critical budget deadline in early October to address its significant national deficit, with political instability threatening the current government.
- The country's 10-year government bond yields have surged to their highest since 2008, reflecting investor concerns over France's escalating debt and political uncertainty.
- Prime Minister Sébastien Lecornu's minority government aims for substantial spending cuts, but faces strong parliamentary opposition, potentially leading to another constitutional bypass or government collapse.
Editor’s Analysis & Impact
The escalating budget crisis in France carries significant implications for both domestic stability and the broader Eurozone. The widening spread between French and German bond yields signals growing investor apprehension, potentially increasing France’s borrowing costs and diverting funds from essential public services and investments. This fiscal strain, coupled with persistent political fragmentation, could further undermine President Macron’s authority and empower extremist political factions ahead of future elections. For the Eurozone, a prolonged French fiscal crisis could reignite concerns about sovereign debt stability, particularly if the European Central Bank remains hesitant to intervene due to its focus on inflation. The situation underscores the urgent need for robust fiscal reforms and political consensus to prevent a deeper economic and political downturn.
Frequently Asked Questions
Q: Why are France's bond yields rising?
A: France's bond yields are rising due to increasing investor concerns over the country's substantial national debt, its large budget deficit, and the ongoing political instability surrounding the critical budget negotiations. Investors are demanding a higher premium to lend to the French government.
Q: What is the 'OAT-Bund spread' and why is it significant?
A: The OAT-Bund spread refers to the difference in yield between France's 10-year government bonds (OATs) and Germany's 10-year government bonds (Bunds). A widening spread, as currently observed, indicates that investors perceive France as a riskier borrower compared to Germany, demanding greater compensation for holding French debt. This is significant as it reflects market confidence in France's fiscal health and political stability.
Q: What are the potential consequences if France fails to pass a budget?
A: Failure to pass a budget could lead to the collapse of the current minority government, triggering further political instability and potentially early elections. Economically, it could result in credit rating downgrades, significantly increased borrowing costs for the French state, and a hampered ability to fund public services and investments, with potential ripple effects across the Eurozone.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category