Surging Mortgage Rates Dampen U.S. Housing Activity as Homebuyer Demand Slumps 19%
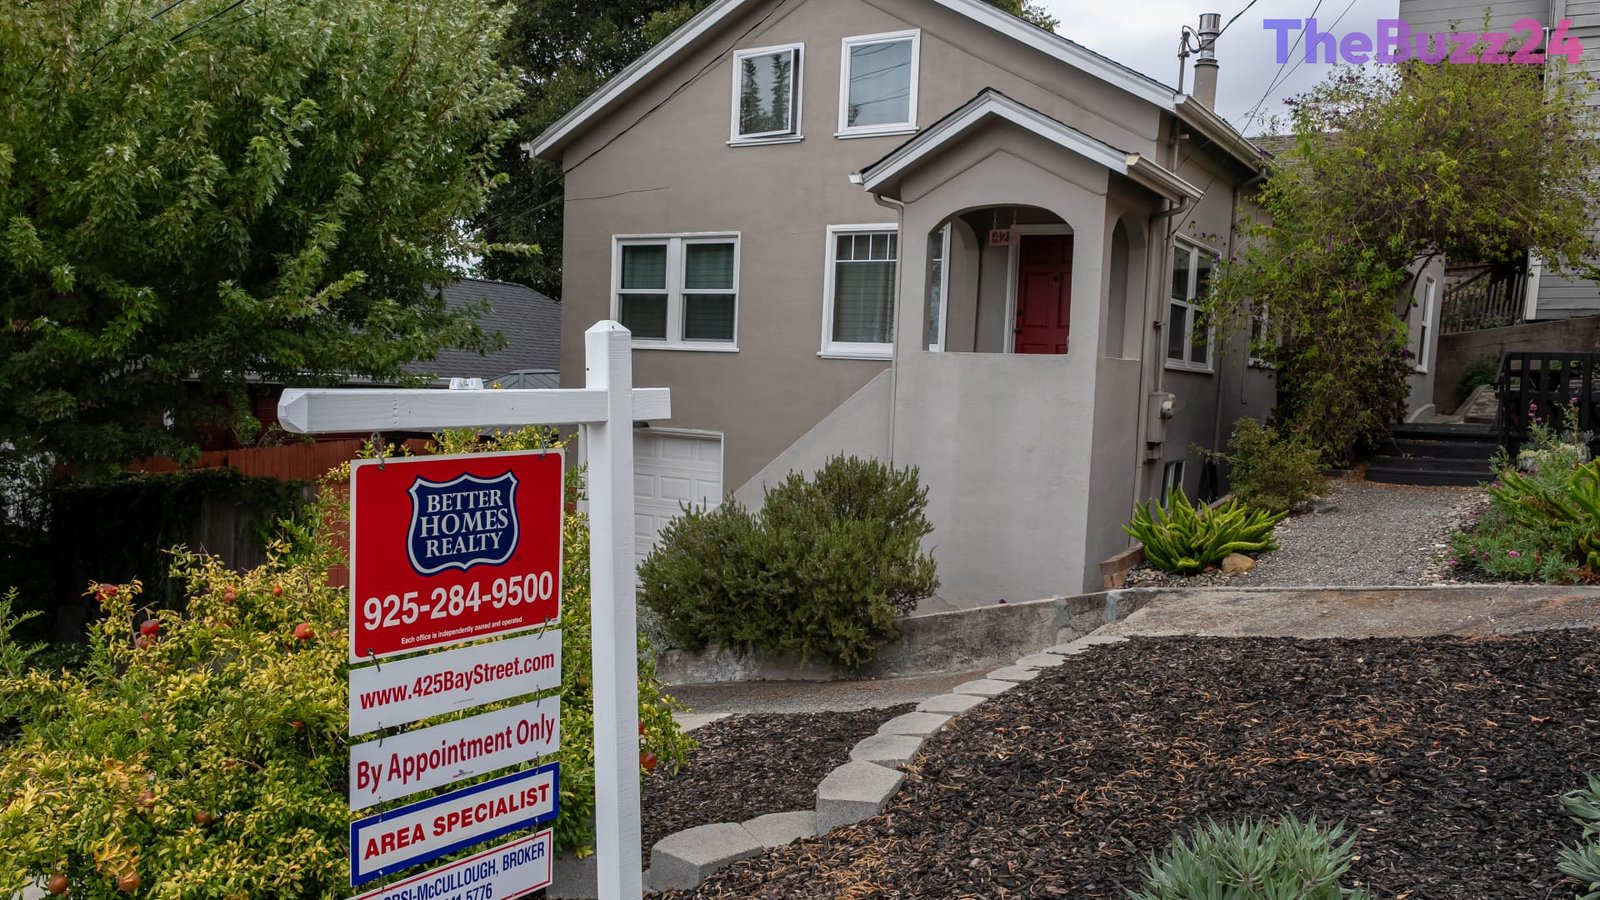
A sudden escalation in borrowing costs is exerting fresh downward pressure on the housing market, leading both prospective buyers and existing homeowners to retreat from real estate transactions. Overall mortgage application volume declined 4.1% on a seasonally adjusted basis week-over-week, reflecting growing consumer hesitation amid sharp rate spikes.
Purchase activity continues to face stiff headwinds, with home purchase applications falling 1% from the previous week and dropping 19% compared to the same period a year ago. Even as inventory levels expand modestly across parts of the country, much of that available supply is clustered at higher price points, offering minimal relief to prospective buyers grappling with elevated property values and soaring financing costs.
The average contract interest rate for standard 30-year fixed-rate mortgages rose to 6.97% before jumping past 7.22% earlier this week. The rapid increase has been driven by broader financial market pressures, notably elevated bond yields fueled by volatile energy prices, sticky inflation metrics, and shifting expectations around Federal Reserve monetary policy. Over a span of less than a week, average rates surged roughly a third of a percentage point, marking one of the steepest near-term increases recorded recently.
Meanwhile, the refinancing segment has contracted significantly due to its extreme sensitivity to rate adjustments. Refinance applications declined 9% week-over-week and plunged 65% relative to the prior year. With current rates sitting considerably higher than year-ago benchmarks, the financial incentive to refinance has virtually vanished for conventional, FHA, and VA loan holders alike.
Key Takeaways
- Home purchase mortgage applications fell 19% year-over-year as 30-year fixed rates jumped past 7.22%.
- Refinance activity dropped 65% compared to the same period last year, effectively halting mortgage refinancing benefits for most borrowers.
- Higher energy costs and ongoing inflation concerns continue to push bond yields upward, dampening housing affordability.
Editor’s Analysis & Impact
The rapid ascent of mortgage rates back above the 7% threshold underscores the ongoing challenge facing the U.S. housing sector. Higher borrowing costs effectively lock in existing homeowners who secured sub-4% rates during previous years, restricting the inventory of moderately priced homes. At the same time, prospective first-time buyers are facing acute affordability constraints due to high home valuations and steep monthly payments. In the near term, housing turnover is expected to remain subdued. As long as economic indicators such as oil prices and core inflation keep the Federal Reserve cautious on rate cuts, bond markets will remain volatile, keeping mortgage rates elevated and constraining broad-based market recovery.
Frequently Asked Questions
Q: Why are mortgage rates rising abruptly?
A: Mortgage rates are rising primarily due to higher bond yields, which have been driven upward by persistent inflation, surging energy prices, and market uncertainty regarding the Federal Reserve's interest rate trajectory.
Q: How significantly has refinance demand dropped?
A: Refinance applications have fallen 9% on a weekly basis and are down 65% compared to the same week last year, as higher interest rates eliminate financial benefits for homeowners.
Q: How does this affect current home prices and inventory?
A: While housing inventory has shown modest gains in certain regions, new listings are heavily concentrated in the higher-end price range, leaving affordable entry-level options constrained despite softening buyer demand.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category