France’s Fiscal Crisis Deepens: Is the Eurozone’s Second-Largest Economy ‘Too Big to Save’?
France is facing a mounting fiscal storm that has sparked warnings from top economists about the country’s long-term financial stability. Nobel laureate economist Paul Krugman recently cautioned that the nation is on an unsustainable fiscal trajectory, burdened by a high debt-to-GDP ratio, massive budget deficits, and escalating interest payments. The situation has raised fears that France, the Eurozone’s second-largest economy, could eventually become “too big to save” if a full-blown debt crisis erupts, potentially overwhelming the intervention capabilities of the European Central Bank (ECB).
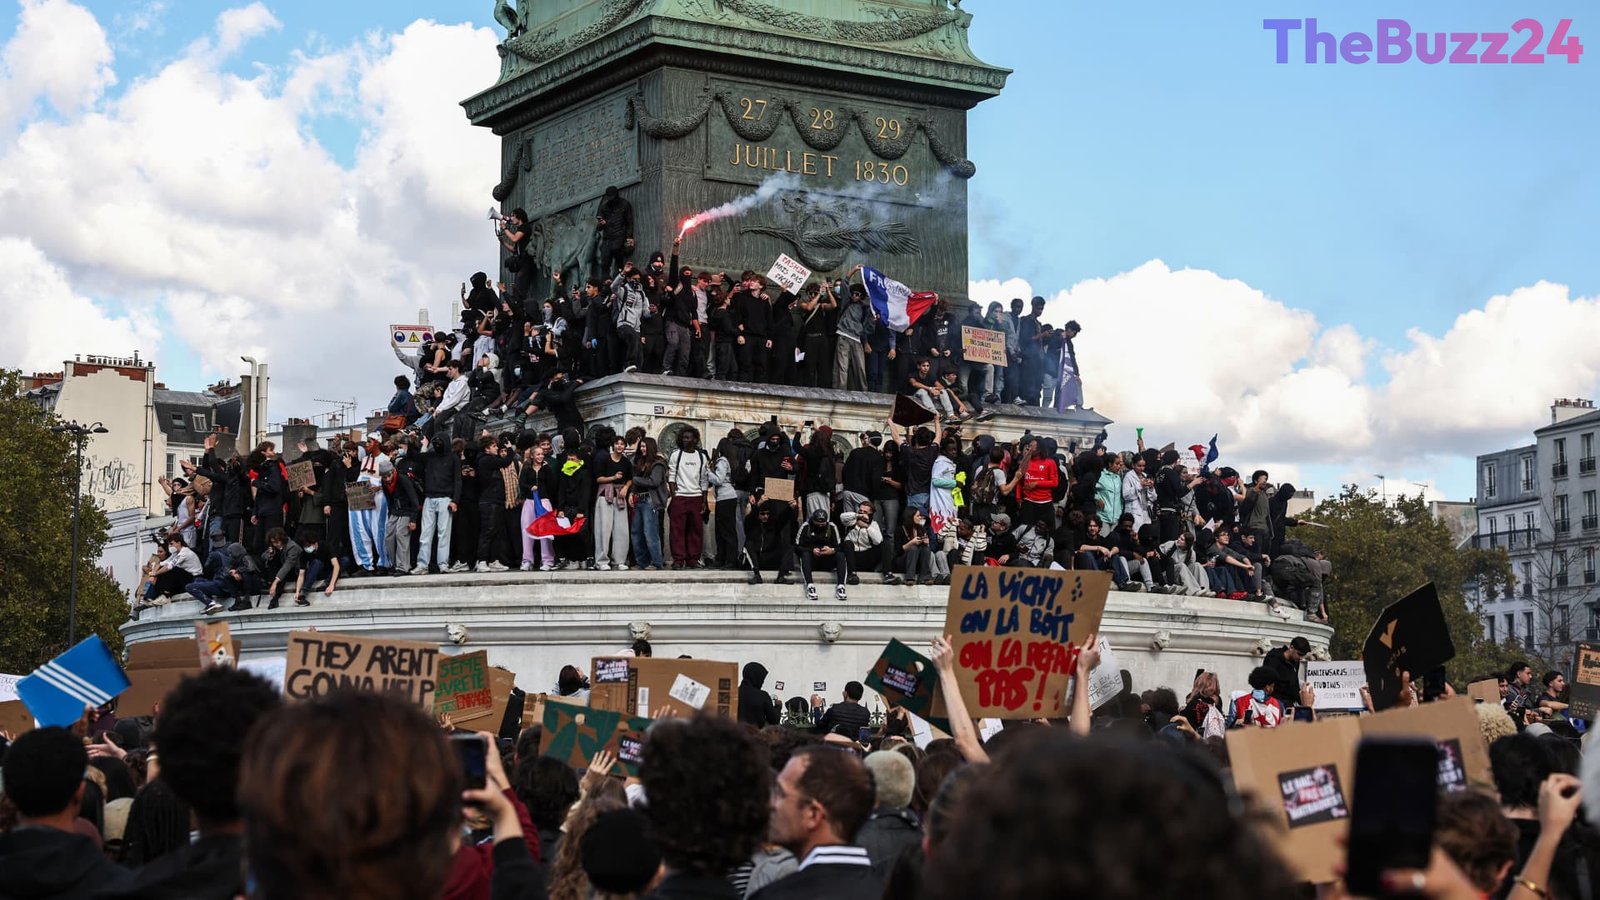
The fiscal pressure comes at a highly volatile time for French politics. Prime Minister Sébastien Lecornu is currently locked in a fierce battle to pass a highly contentious 2027 budget. The proposed budget aims to implement tens of billions of dollars in fiscal consolidation, a move that has triggered widespread public backlash, including intense student protests over the underfunding of the education system. Critics point out that structural issues, particularly France’s reluctance to adjust its relatively low retirement age in the face of an aging demographic, continue to exacerbate the nation’s structural deficit.
Drawing parallels to the European Sovereign Debt Crisis of 2009–2012, experts warn of a potential vicious cycle where a loss of investor confidence could trigger capital flight, driving up borrowing costs and pushing the government toward default. During the previous crisis, the ECB managed to calm markets with its famous pledge to do “whatever it takes,” but that reassurance was contingent on highly unpopular austerity measures in southern Europe. A bailout for an economy as massive as France’s would not only be astronomically expensive but also politically explosive across the European Union.
In response to the growing anxiety, former ECB President Jean-Claude Trichet has urged French lawmakers across the political spectrum to act responsibly and find a credible compromise. Trichet emphasized that while the ECB possesses powerful stabilization tools, such as the unused Transmission Protection Instrument (TPI), any external assistance is strictly conditional. He stressed that France must first restore its own credibility with international markets and demonstrate a commitment to fiscal discipline before expecting central bank intervention.
Key Takeaways
- Nobel laureate Paul Krugman warns that France's mounting debt and high deficits put it on a fiscally unsustainable path that could trigger a Eurozone crisis.
- Prime Minister Sébastien Lecornu faces severe political resistance and public protests as he attempts to pass a 2027 budget featuring massive fiscal consolidation.
- Former ECB President Jean-Claude Trichet has called on French politicians to restore market credibility, noting that central bank rescue tools require domestic fiscal responsibility.
Editor’s Analysis & Impact
The fiscal standoff in France represents a critical vulnerability for the entire Eurozone. As the bloc’s second-largest economy, France’s financial health is deeply intertwined with the stability of the euro. Unlike smaller nations like Greece or Portugal, which required extensive bailouts a decade ago, France’s sheer economic scale means a sovereign debt crisis could easily overwhelm existing European safety nets. The core of the issue is political paralysis; the French government is caught between the necessity of fiscal consolidation to appease bond markets and intense domestic resistance to austerity and pension reforms. If French policymakers fail to deliver a credible deficit-reduction plan, rising bond yields could force the ECB’s hand, testing the limits of its monetary tools and triggering a fresh wave of political friction between northern and southern European member states.
Frequently Asked Questions
Q: Why is France facing a potential debt crisis?
A: France is struggling with a high debt-to-GDP ratio, large budget deficits, and rising interest rates on its government debt. Structural issues, such as a low retirement age relative to its aging population, combined with political difficulties in passing fiscal consolidation measures, have heightened investor anxiety.
Q: What is the 'too big to save' concern?
A: The term refers to the risk that France's economy is so large that the financial resources required to bail it out during a sovereign debt crisis would exceed the political and financial capacity of the European Central Bank and other Eurozone members.
Q: What tools does the European Central Bank have to help France?
A: The ECB has several stabilization mechanisms, including the European Stability Mechanism and the Transmission Protection Instrument (TPI). However, activating these tools requires the struggling nation to formally request aid and commit to strict fiscal discipline and economic reforms.
AI Disclosure: This article is based on verified data and official reports. Our Team and AI have cross-referenced every financial detail with primary sources to ensure total accuracy.
More from this Category